Loans For Bad Credit: Repair Your Credit Record Before You Borrow
An old default does not make every application impossible, but it changes what lenders need to see. This guide explains credit-report corrections, affordability, lawful lending and the warning signs of high-cost offers in Pakistan.
The Short Answer
Start by checking the accuracy of your banking history, resolving arrears where possible and setting an honest repayment budget. Do not pay a stranger to “erase” an eCIB entry or rely on an app promising approval without checks.
Programme Facts At A Glance
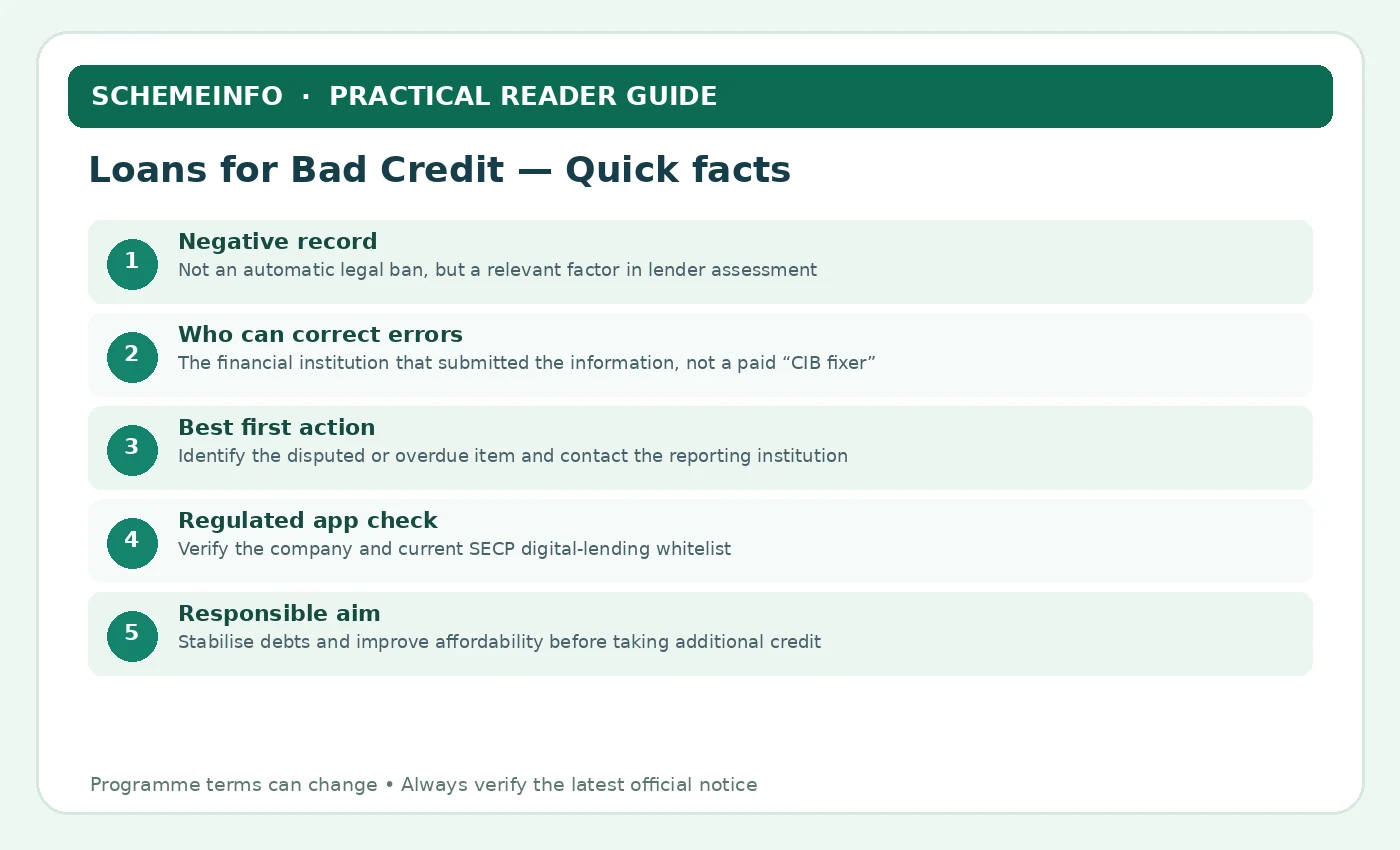
These are the central published facts for the Loans for Bad Credit, not a guarantee of admission, approval or an open registration window. The references at the bottom distinguish current official pages from historical phases.
| Negative record | Not an automatic legal ban, but a relevant factor in lender assessment |
|---|---|
| Who can correct errors | The financial institution that submitted the information, not a paid “CIB fixer” |
| Best first action | Identify the disputed or overdue item and contact the reporting institution |
| Regulated app check | Verify the company and current SECP digital-lending whitelist |
| Responsible aim | Stabilise debts and improve affordability before taking additional credit |
Eligibility After An Adverse Credit Record
Begin with the responsible institution’s written eligibility rules for Loans for Bad Credit. These checks are not a promise of approval; eligibility is decided through the named programme’s actual verification process.
- Valid CNIC and lawful authority to apply under the selected lender’s policy.
- Verifiable income or cash flow sufficient to repay after essential costs.
- Accurate disclosure of current loans, outstanding arrears and credit-report issues.
- Compliance with the lender’s minimum age, residency and other product conditions.
- A legitimate licensed bank or SECP-regulated lender rather than an anonymous loan application.
- A written offer with understandable total cost, repayment and consequences of non-payment.
Evidence For Credit Review And Correction
Keep essential records legible and separate from optional supporting papers. confirm which forms the responsible office requires before sharing identity or family information.
- CNIC and applicant-owned contact details.
- Recent income and salary, business or cash-flow evidence where required.
- Bank statements and a list of actual existing debt obligations.
- Credit-report dispute evidence if an entry is incorrect, including payment receipts and lender statements.
- A written household budget showing affordable repayment capacity.
- Copies of lender complaints, rejection messages and correspondence if seeking a correction.
How Bad-Credit Applications Are Assessed
The following sections unpack the Loans for Bad Credit rules, common misunderstandings and evidence needed for a responsible decision. Check the original official source whenever a condition affects your eligibility.
What Bad Credit Actually Means
A poor credit record can arise from overdue instalments, unpaid balances or inaccurate data in a lender’s report. The consequences vary by the product and institution. A one-time disputed late-payment entry and a continuing default are not the same financial situation.
Why An Earlier Rejection Matters
A previous application may have failed because of credit history, unverified income, too much existing debt or a policy restriction. Applying repeatedly without understanding the reason can waste time. Request the legitimate institution’s available explanation and review your original declaration for accuracy. A borrower with insufficient disposable income needs a different strategy from someone whose report contains the wrong account.
How Regulated Lenders Review Credit
SBP’s consumer-finance rules require lenders to consider credit information and verify income, fixed expenses and existing borrowing. Approval is discretionary and based on risk as well as identity. A salary slip with large automatic loan deductions may leave less repayment capacity than gross pay suggests.
Credit Bureaus And The Right Record
Pakistan has private credit bureaus recognised under the credit-bureau regulatory framework, and SBP provides information about credit data and consumer rights. A disputed amount should be supported by payment receipts and lender records, not just a social media complaint.
Dispute A Credit Error Without Paying A Middleman
Before applying again, ask the institution that recorded the borrowing for an itemised account statement showing principal, penalties, payments and any remaining arrears. An eCIB report reflects participating institutions’ submitted information; correction normally begins with the reporting institution, not an individual offering instant record deletion.
For example, a borrower may have a bank receipt showing the final instalment cleared in March, while a later report still indicates an outstanding amount. Request written reconciliation from the lender, keep the complaint reference and escalate through its official complaint mechanism if the record is not corrected. A documented error is different from an accurately reported late payment.
Avoid multiple hurried applications during a dispute. Each new lender may ask for explanations, and repeated incomplete forms create more confusion. A clean, consistent documentary trail improves credibility even when the past problem cannot simply disappear.
- Collect repayment receipts and a current settlement statement
- Raise discrepancies with the lender in writing and save the reference number
- Never pay a purported “credit clearing” service without regulated authorisation
Credit Report Accuracy, Safe Lenders And Affordability
Correcting Inaccurate Information
A mistake in account identity, settlement date or outstanding balance should be raised with the data provider and relevant complaint process. Credit information is not safely corrected by paying a stranger. A paid-off microfinance facility still shown as overdue should be supported by settlement records before escalation.
Repayment Affordability Comes First
An expensive emergency loan may temporarily pay an older instalment while creating another due date. A sustainable plan begins by comparing all debt payments with household income. List essential expenses, current creditors and unavoidable due dates before considering new credit. Borrowing Rs 40,000 to service a Rs 35,000 missed payment can leave a larger problem when new fees and penalties fall due.
Safer Alternatives To Immediate Borrowing
Options can include negotiating a documented repayment arrangement, reducing discretionary spending, seeking legitimate employer support or comparing a smaller regulated facility where eligible. A family repairing noncritical appliances may benefit more from a smaller staged purchase than a 30-day high-fee loan.
Risks Of Guaranteed-Approval Advertisements
Claims such as “no checks, no documents, any defaulter approved” are common red flags. Anonymous apps may seek invasive permissions or upfront payments. Verify the exact company and app through the regulator’s latest official lists, not the ratings or appearance of a download page. A demand for money to remove your name from a credit blacklist should be questioned immediately.
Costs, Evidence And Applicant Decisions
Understanding SECP Digital Lending Approval
SECP publishes a dated whitelist of digital lending apps run by licensed non-bank finance companies. It also publishes notices about reported illegal platforms. These resources are separate from bank licensing. A familiar logo on social media does not confirm that the download link points to the approved app.
Bank-Versus-App Complaint Routes
Banking complaints may be handled initially by the bank and then through appropriate SBP and Banking Mohtasib arrangements, while a digital NBFC complaint uses the relevant regulatory channels. Identify the legal lender first and follow the route that governs that entity. A bank account issue should not automatically be filed as a complaint about an unrelated digital-app company.
What A Debt Restructuring Request Involves
A lender may sometimes consider altered instalments or a settlement plan, but the terms depend on its policy and the borrower’s circumstances. It should never be described as an automatic legal right. A verbal promise from a collector is not as protective as a written arrangement issued by the lender.
Why Multiple Applications May Hurt The Plan
Applying to many lenders in one week can create confusion and lead to inconsistent income and debt disclosures. It also raises the chance of sending sensitive information to unverified services. Choose one suitable regulated route after understanding the full costs rather than copying CNIC details into every page. The best next loan is not necessarily the fastest one; it is the one that fits the actual repayment capacity.
Troubleshooting, Safer Alternatives And Next Steps
When A Guarantor Becomes Liable
A guarantor can have legal obligations if the principal borrower fails to pay. A bad-credit borrower should not pressure relatives into signing without seeing the original agreement. A family member may damage their own finances by backing a facility they assumed was only a reference letter.
Protecting Dignity While Disputing A Debt
Credit problems can be stressful, but harassment and unfair treatment should be raised through documented complaint channels. Use the lender’s complaint unit first where appropriate, then the authorised regulator or dispute forum. Threatening messages or demands to share personal contacts are not reliable evidence of a lawful collection process.
A Step-By-Step 90-Day Recovery Plan
Over the next three months, a borrower can verify debts, stop unnecessary new applications, correct mistakes and create a plan for on-time payments. Improvement usually needs consistent financial behaviour, not a paid shortcut. A household that restores predictable repayments may qualify for more suitable financing later without an expensive instant-loan detour.
When Not Borrowing Is The Safest Decision
If repayment would require another new loan or the expense is not essential, waiting can prevent additional defaults and fees. Official lender approval does not prove an offer is appropriate for a household. A short-term emergency app may be a poor choice for a long-term income shortfall.
Understanding The Reason For Past Refusal
Use the named programme’s actual rules and documents to evaluate these decisions. Each item below addresses a different obstacle that applicants commonly face.
Separate A Genuine Overdue From An Incorrect Entry
The words bad credit can refer to an unpaid loan, late instalments, a data error, identity misuse or a lender’s decision that current commitments are too high. These cases require different actions. SBP explains that eCIB reports provide credit information rather than an official declaration that a person is prohibited from ever borrowing.
- List each known lender, account, outstanding balance, instalment date and any proof of settlement.
- For a disputed loan, ask the reporting institution for a written transaction and reporting explanation rather than relying on screenshots.
- If the record is wrong, request a correction from the institution that submitted it; SBP states that eCIB itself does not simply rewrite a record on request.
- Keep complaint references and settlement receipts in case the same entry affects a later regulated application.
A correct record of missed payments may remain visible for a period even after settlement. That is different from an unresolved outstanding balance; do not pay someone to promise immediate erasure.
Measure What Another Instalment Would Do
A new loan may look attractive because it pays an urgent bill, but it adds another fixed obligation to income that is already strained. Before borrowing again, create a monthly household cash-flow sheet and include unavoidable expenses. The right question is whether the new instalment leaves a sustainable surplus in a difficult month.
- Write down net take-home pay or conservative business income, not an optimistic gross sales number.
- Deduct rent, food, utilities, transport, essential medicines and all existing minimum repayments.
- Compare the remaining amount with the new instalment, compulsory fees and any irregular income risk.
- If there is a deficit, ask an existing lender about a documented restructuring or repayment arrangement before seeking new debt.
Regulated lenders assess risk and affordability themselves. A calculator can help decide whether to apply, but it cannot promise that an application will pass underwriting.
Build A Repayment Budget That Survives A Bad Month
Lenders may approve a smaller amount than requested because they assess existing instalments and regular commitments. Calculate monthly take-home income after rent, groceries, utilities, travel, health costs and current debt. Do not treat an irregular overtime bonus as guaranteed monthly income.
Consider a household earning Rs 85,000, with Rs 66,000 in unavoidable spending and Rs 6,000 in existing debt instalments. The remaining Rs 13,000 is not automatically safe for a new Rs 12,000 repayment. A medical bill or unexpected repair could push the household straight back into arrears. A less expensive purchase or delayed borrowing can be a better outcome.
A guarantor or security should not become a shortcut around a failed affordability test. If the loan is for stock or equipment, use conservative cash receipts rather than projected best-case sales.
- Write a three-month expense history before requesting a loan
- Stress-test repayment against reduced income
- Review the total cost and default charges, not only the first instalment
Record Repair, Scams And Sustainable Repayments
Use the named programme’s actual rules and documents to evaluate these decisions. Each item below addresses a different obstacle that applicants commonly face.
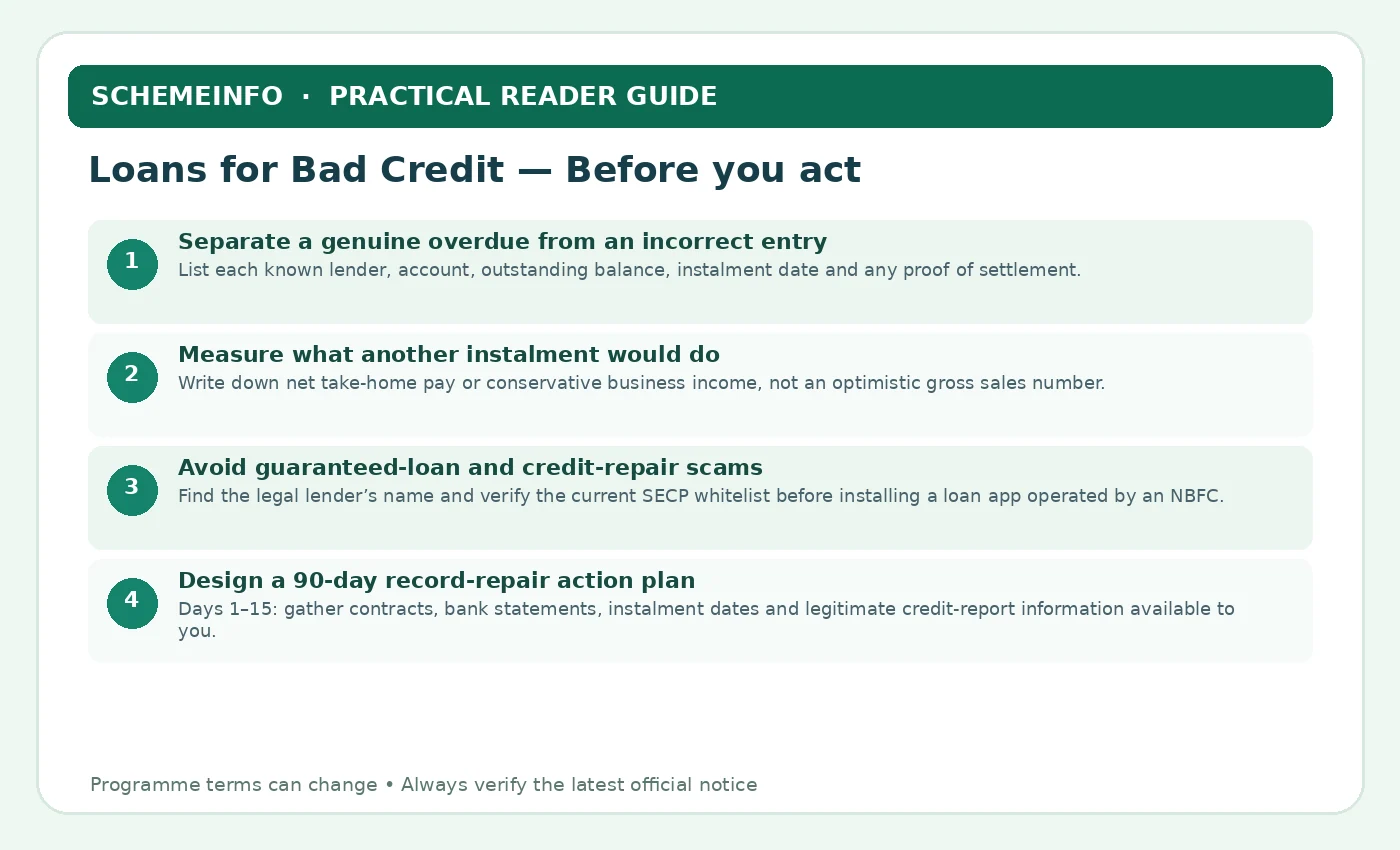
Avoid Guaranteed-Loan And Credit-Repair Scams
A claim that bad credit is irrelevant, an approval is guaranteed or a bureau record can be erased instantly is a warning sign. A professional website, social-media testimonials and a recognisable logo do not show the business is licensed. Digital lenders and collection conduct should be checked using the correct regulator and current list.
- Find the legal lender’s name and verify the current SECP whitelist before installing a loan app operated by an NBFC.
- Reject requests for an advance personal transfer supposedly needed to unlock an approved loan.
- Never disclose an OTP, account password or complete banking credentials to a telemarketer or “credit repair” agent.
- Read the exact lending amount, net proceeds, repayment dates, fees, data permissions and complaint process before accepting.
If debt collectors threaten harassment or misuse private data, preserve evidence and use legitimate regulatory or law-enforcement reporting routes as appropriate.
Design A 90-Day Record-Repair Action Plan
Improvement is usually a documented sequence rather than a single online trick. In the first month the borrower can identify the debts and contact the lenders. In the second, the focus can be on correcting records and making agreed payments. The third month is for checking that receipts, statuses and budgets remain consistent.
- Days 1–15: gather contracts, bank statements, instalment dates and legitimate credit-report information available to you.
- Days 16–30: send written disputes for factual errors and negotiate feasible repayment solutions for genuine arrears.
- Days 31–60: document each payment and follow up with the reporting lender on corrections or current account status.
- Days 61–90: reassess income stability and borrow only if a legitimate, affordable product matches an essential purpose.
A fresh application should be a reasoned choice after finances stabilise, not proof that the old problem has vanished.
Bad-Credit Borrowing: Household Payment Stress Test
Consider someone with Rs 65,000 monthly take-home income and Rs 54,000 of essential living costs plus existing instalments. A new product demanding Rs 12,000 each month would create a deficit before unexpected expenses.
| Take-home income | Rs 65,000 each month |
|---|---|
| Essentials + existing repayments | Rs 54,000 per month |
| Remaining before new loan | Rs 11,000 |
| Proposed new monthly instalment | Rs 12,000 |
| Shortfall even before emergencies | Rs 1,000 monthly deficit |
What The Comparison Means Before You Act
- A negative budget makes borrowing more dangerous regardless of an advertised approval rate.
- Request a written statement and correction of inaccurate credit items through the reporting lender.
- Compare realistic debt restructuring with the full cost of taking new money.
- Reject anyone promising a guaranteed cure for an eCIB record in return for advance fees.
The responsible decision in this example is not accepting a new Rs 12,000 instalment without changing the budget or other obligations.
Illustrative worksheet: Figures are educational examples, not a real lender quotation or confirmed approval. Always use the responsible institution’s current written terms.
Two Realistic Loans For Bad Credit Situations
These scenarios are illustrations, not real applicants, case-law findings or promised outcomes. Their purpose is to show what a careful next decision looks like when one key detail is uncertain.
Settled Debt Still Appears On Record
After clearing an overdue balance, a borrower is offered an expensive “instant CIB cleaning” service. The borrower instead retains the bank settlement proof, requests the reporting lender’s update and checks SBP’s actual reporting guidance.
Worker Offered Emergency Cash At A High Total Cost
A worker with existing arrears sees a loan-app advertisement. She compares net disbursement with total repayment and basic living costs; the budget would be negative, so she considers negotiating an instalment plan rather than taking the app loan.
Your Next Steps
Follow the official procedure for this specific topic. A submitted form or preliminary status is never proof of final selection or disbursement.
- Identify the real credit problem: Record whether the issue is overdue, an inaccurate report, income or existing debt burden.
- Collect financial evidence: Gather contracts, statements, paid receipts and correspondence from relevant lenders.
- Request correction properly: Approach the reporting institution for factual errors and preserve the dispute reference.
- Negotiate genuine arrears: Ask for a feasible written payment or restructuring arrangement where appropriate.
- Calculate a safe budget: Deduct essential expenses and current instalments before considering any new liability.
- Check a potential lender: Verify licensing or SECP app listing and read the complete cost, privacy and collection conditions.
- Avoid harmful repeat borrowing: Do not borrow when the resulting instalment causes a deficit or depends on another quick loan.
Spot An Unsafe Credit-Repair Or Loan Offer
A digital advertisement promising “guaranteed approval for bad credit” is not evidence of a registered lender. Compare the legal company name with the relevant regulator’s current list. Licensed non-bank lending apps are listed by the SECP; banking services should be checked through the appropriate State Bank-regulated institution.
Never send OTP codes, passwords or access to private contact lists to a supposed loan officer. A request to pay a processing charge into a personal wallet before any formal agreement is another red flag. Legitimate terms should identify the borrowing party, disbursement amount, fees, dates and complaint channel.
Where the debt is already unaffordable, speak to the current lender about a documented hardship arrangement before taking fresh high-cost credit. Borrowing to silence an aggressive collector can deepen the problem rather than resolve it.
- Check the exact operating company and product name
- Request a written repayment schedule and fee summary
- Retain evidence of threats or unlawful collection practices
Official Sources And How To Verify Updates
Official programme notices and lender instructions take precedence over older articles, screenshots and social-media posts. Check the precise phase, date and applicant category before submitting personal details.
Related SchemesInfo Reading
For related topics, explore the following site searches. Each subject has its own rules and application procedure, so do not transfer eligibility requirements between programmes.