Loan Apps In Pakistan: Check SECP Licensing Before Sharing Your CNIC
A loan app can deliver cash quickly but may carry a very short repayment term, costly fees or intrusive data permissions. Learn to verify a company against the regulator’s current list and compare the actual money received with the money due.
The Short Answer
SECP publishes an official white list of lending apps operated by licensed non-bank finance companies, updated during 2026. Check the exact app and legal operator against the latest version before installing or uploading identification. An app’s popularity, search ranking or logo is not regulatory approval.
Digital Lending Safety Snapshot
These are the central published facts for this programme, not a guarantee of admission, approval or an open registration window. The references at the bottom distinguish current official pages from historical phases.
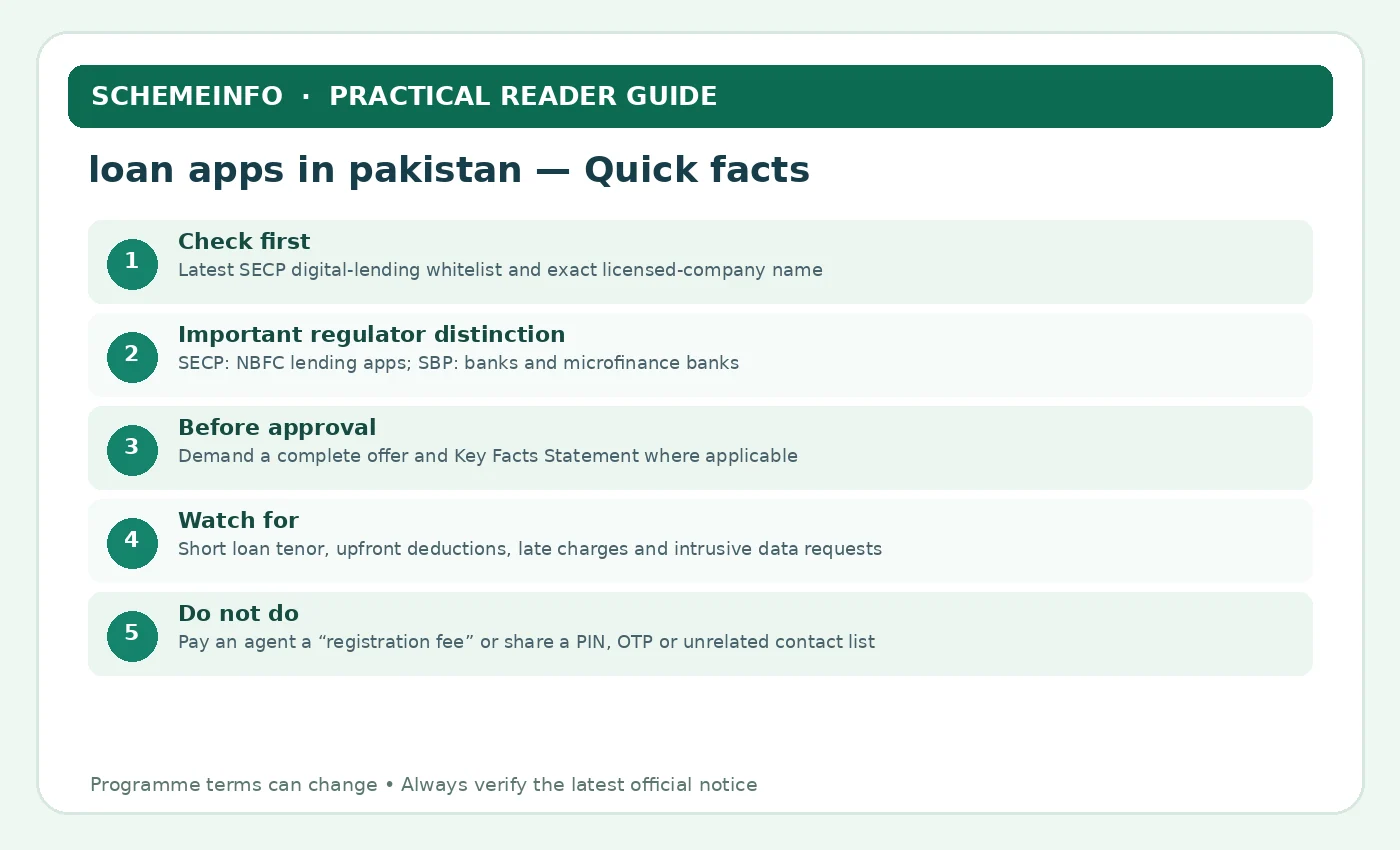
| Check first | Latest SECP digital-lending whitelist and exact licensed-company name |
|---|---|
| Important regulator distinction | SECP: NBFC lending apps; SBP: banks and microfinance banks |
| Before approval | Demand a complete offer and Key Facts Statement where applicable |
| Watch for | Short loan tenor, upfront deductions, late charges and intrusive data requests |
| Do not do | Pay an agent a “registration fee” or share a PIN, OTP or unrelated contact list |
Lender Eligibility And Borrower Suitability
Begin with the responsible institution’s written eligibility rules for loan apps in pakistan. These checks are not a promise of approval; eligibility is decided through the named programme’s actual verification process.
- Applicant satisfies the particular licensed lender’s age, identity, residency and underwriting requirements; there is no single eligibility rule for all apps.
- Applicant can document enough income or cash flow to repay on the agreed date after essential expenses.
- Applicant uses an authentic application distributed or linked by the approved lending entity.
- Applicant understands the schedule, total cost, late-payment terms, deductions and data/privacy permissions before accepting.
- Applicant can receive communications through their own registered phone number and verify the lender’s full company name.
Documents For Loan Apps In Pakistan: Records And Proof
Keep essential records legible and separate from optional supporting papers. confirm which forms the responsible office requires before sharing identity or family information.
- CNIC and mobile number only as requested through an authenticated licensed lender’s process.
- Income or employment information, where the chosen regulated app actually requires it.
- Bank or wallet details for disbursement and repayment, supplied only in an official secure form.
- Credit consent or credit report permissions that the lender clearly discloses.
- Copy of the offer, fee schedule, repayment date and electronic agreement retained by the borrower.
- Avoid supplying passwords, social-media logins, unrelated family contacts or advance fees requested outside the app.
Verify The App And Its Legal Operator
Begin at the SECP website rather than trusting a link in an advert. Its current digital-lending white list identifies applications and the associated licensed non-bank finance company. Spellings, ownership and publication dates matter; a copied logo or a similarly named application could be unrelated to the licensed firm.
A banking or microfinance-bank app may instead fall under State Bank supervision. The regulator to consult depends on the legal entity and product, not simply whether the service uses Android or iOS. If you cannot find a clear operator, company address, licence or published contract, do not submit a CNIC photograph to investigate.
Check the latest SECP document directly when you apply. Lists change: an old screenshot is not reliable proof of the present position. Do not treat absence from an illegal-app watchlist as an affirmative licence.
- Read the SECP list date, exact application name and operator
- Confirm the official store listing belongs to that operator
- Refuse installation links sent through unknown chats
How Digital Lenders Assess Borrowers
Use these programme-specific details to check the official route and to avoid interpreting a rule more broadly than it was written.
Start With SECP Approval, Not A Star Rating
Search rankings and five-star reviews do not establish legal authorisation to lend. SECP publishes an official list of digital apps operated by licensed non-bank finance companies. Check the date on the newest whitelist, the company behind the app and whether its exact spelling matches the listing. An app may change owners or names, so use the regulator’s latest source rather than an old screenshot shared in a group. an official bank or SECP reference is more valuable than sponsored ranking language.
How To Read The Whitelist
SECP separates different categories of digital finance, including nano lending and other financial services. One listed product might offer salary-related access, another instalment purchases and another short-term cash lending. Licensing of one service should not be misread as approval for every related product. If the exact company name is missing or unclear, verify with the regulator before installing or submitting identity documents. A person considering loan apps in pakistan should calculate monthly surplus using conservative figures.
What “Best” Should Mean For A Borrower
The best option is not necessarily the fastest app or the one advertising the largest initial limit. Compare licensing, actual funds received, total charges, repayment flexibility, privacy policy, transparent complaint channels and whether it fits the intended purpose. A product with a slower manual check can still be safer than an instant offer with undisclosed deductions. A loan is only useful when repayment remains realistic. Under loan apps in pakistan, the smallest advertised number is not automatically the cheapest loan.
Compare The Cash You Receive With The Cash You Owe
Suppose a nominal loan offers Rs 20,000, deducts a service fee at disbursement and requires a larger repayment in a few weeks. The apparent rate based on the headline principal can disguise the true cost of the money received. Write down the net disbursed cash, every fee, exact due date and total rupees payable. In the context of loan apps in pakistan, this difference can change both the applicant’s next action and expectations. Someone searching for loan apps in pakistan might be under time pressure, which makes fake release charges particularly dangerous.
The Licensed App, Cash Cost And Data Permissions
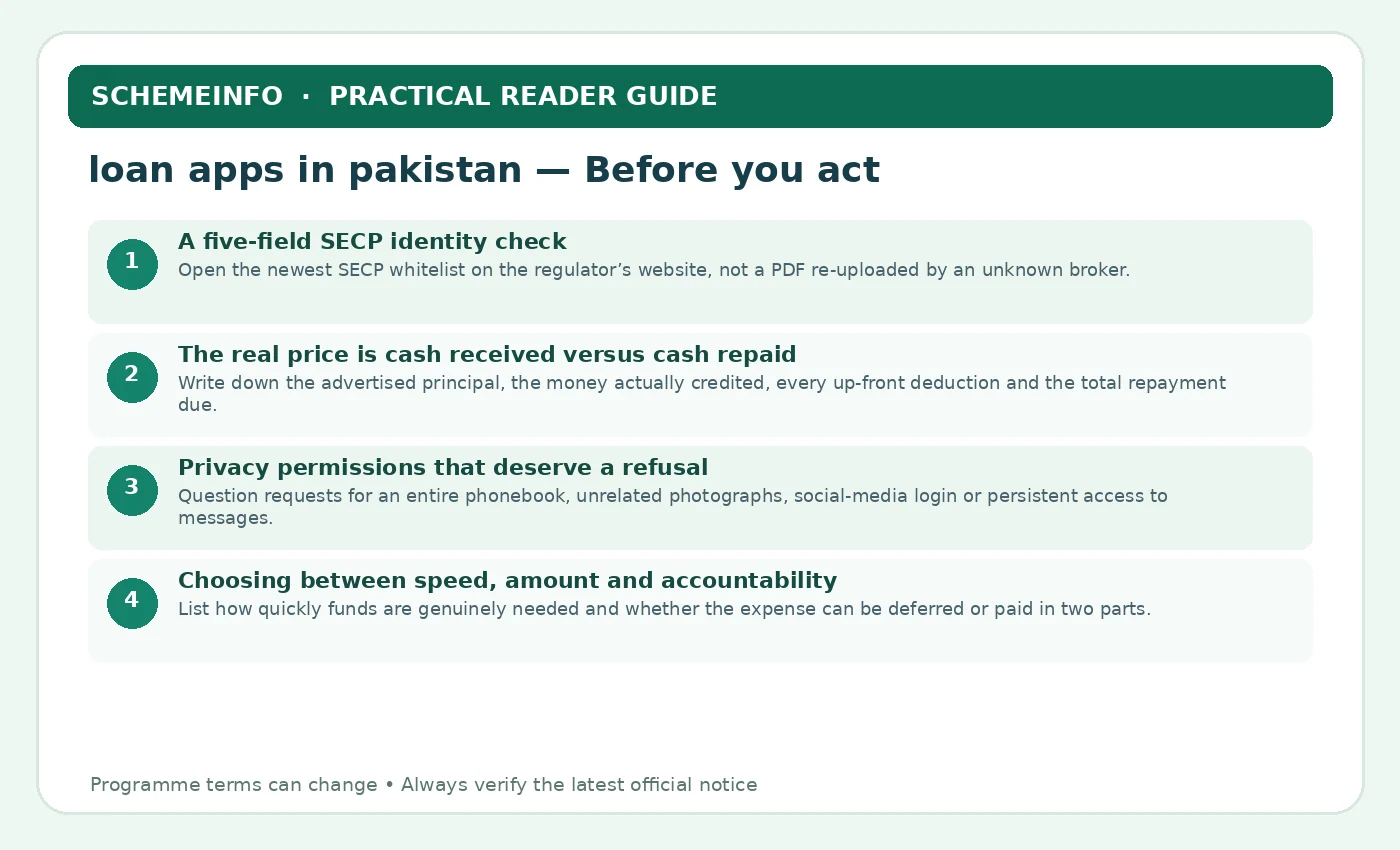
Privacy Permissions Need A Separate Review
A phone app can ask for access to contacts, photographs, location or device files, but the existence of a permission request does not make it appropriate. Read the lender’s privacy disclosures and understand which information is necessary to provide the service. Be suspicious of broad demands unrelated to credit assessment or debt collection. A credible guide to loan apps in pakistan needs to acknowledge limits as clearly as the possible benefits. In assessing loan apps in pakistan, the borrower should assume that a difficult month can happen.
Why Illegal-App Lists Are Not Enough
SECP also publishes reports of unauthorised or illegal lending applications and platforms. This is helpful for recognising known problems, but the absence of a name is not an approval signal: warning lists may lag the latest fraudulent launches. Check the positive approved-app list and the entity’s regulated status. An unfamiliar copycat name can be enough reason to stop. People researching loan apps in pakistan should keep the original document date beside any figures they encounter. gather only the documents requested by a verified institution and keep copies of the versions submitted.
Read The Repayment Screen Line By Line
Before agreeing, identify any processing charge, service charge, late fee, loan insurance, auto-debit consent or prepayment rule. Confirm whether repayment is a lump sum or instalments, and whether a missed date triggers compounding charges. Keep screenshots of the complete offer and the terms agreed to. A rushed tap at the final step can leave a borrower with a much harder obligation than expected. Any decision involving loan apps in pakistan is stronger when the applicant can show accurate records and a manageable budget. An enquiry about loan apps in pakistan can end with a refusal or a smaller offer; that is not a reason to accept opaque charges.
What To Do After A Suspicious Demand
An offer asking for a fee by personal bank transfer before disbursing money is a strong red flag. Do not send OTPs or allow remote-access software to control your phone. Take screenshots, stop communicating through the unverified channel and confirm the company using regulator or official lender contact information. Where fraud has occurred, make a documented report through relevant channels. The practical value of loan apps in pakistan depends on the approved conditions, not the size of a headline. Where the search is loan apps in pakistan, the correct product could be an asset loan, seasonal farm finance or a smaller livelihood facility rather than consumer cash.
Choosing The Right Borrowing Route
Beyond the headline amount, these details help a borrower compare the offer, prepare reliable evidence and avoid avoidable costs. Financial terms and availability always depend on the actual lender or programme.
A Five-Field SECP Identity Check
A comparison page may praise an app for speed, but a borrower should first prove that the exact legal lending entity and product are authorised. Branding can change faster than review websites.
- Open the newest SECP whitelist on the regulator’s website, not a PDF re-uploaded by an unknown broker.
- Match the app’s exact spelling, operating company and category with the official entry, including whether it is a lending NBFC.
- Check the developer name and privacy policy from the real app-store listing; an imitation may copy a familiar icon.
- Confirm the payment and customer-support channels from the same authorised company rather than a WhatsApp number in a promotion.
- If the product is described as bank lending, verify the bank directly instead of assuming an NBFC whitelist covers every digital provider.
Approval of a company does not mean that every fee quoted in a message is correct. Regulatory identity and contract review are two separate checks.
The Real Price Is Cash Received Versus Cash Repaid
A small short-term loan can look harmless until deductions and late fees are combined. Read the financial offer in rupees and dates rather than just annual percentage language.
- Write down the advertised principal, the money actually credited, every up-front deduction and the total repayment due.
- Divide the full cost by the usable cash received when comparing two offers with similar terms; do not compare headline principals alone.
- Check whether the repayment occurs in one lump sum after a few weeks or by instalments that match salary dates.
- Ask for the Key Facts Statement and inspect all collection, rollover and late-fee provisions before tapping “Accept”.
- Treat a second loan offered to repay the first as a warning sign; it can compound fees and expose other household income.
A borrowing decision should survive an ordinary bad month. If one missed date creates an unmanageable balance, the product is too fragile.
Borrower Decision Worksheet: Loan Apps In Pakistan
Work through these questions before providing personal records or accepting a financing offer. This is an independent decision tool, not a lender application form. Write the evidence or published rule that answers each question.
- Decision 1: Which named lender, department or licensed company would make the actual decision?
- Decision 2: Is this the currently authorised application route, and what date is the guidance from?
- Decision 3: What amount would reach my account after processing and other authorised deductions?
- Decision 4: What exact dates and amounts would I repay, including any compulsory fees?
- Decision 5: How much remains after rent, food, utilities, transport and all existing repayments?
- Decision 6: What happens to collateral, guarantors or credit records if I miss a payment?
- Decision 7: Can I prove the spending purpose and funds use with appropriate business or personal records?
- Decision 8: Where is the responsible organisation’s official complaints and correction channel?
Four Checks Specific To This Financing Question
If the product is described as bank lending, verify the bank directly instead of assuming an NBFC whitelist covers every digital provider.
Treat a second loan offered to repay the first as a warning sign; it can compound fees and expose other household income.
If harassment occurs, record the dates, callers, threats and screenshots before changing passwords or escalating formally.
Save a screenshot of the final offer, signed agreement and payment receipt in a secure location before funds are transferred.
The purpose of a worksheet is to prevent one misleading number from deciding the entire choice. Compare the original source, the actual offer and the household budget. If any one of these is missing, the sensible next action is further verification rather than signing.
The Small-Loan Cost Trap
A fee described as a processing deduction changes the effective cost of borrowing. Suppose an app approves Rs 20,000, deducts Rs 2,000 at disbursement and requires Rs 23,000 in 30 days. The borrower receives Rs 18,000 but owes Rs 23,000: a Rs 5,000 gap for one month. The illustrative cash difference should be assessed against the period and any further charges, not simply described as a low headline percentage.
A very short maturity is particularly dangerous for workers paid irregularly or at month-end. A loan taken on the 25th and payable before the next salary arrives can trigger repeated borrowing. Ask whether the app offers a genuine hardship process, clear due-date changes and direct complaint channels.
Compare at least two licensed products using an identical amount received, repayment date, fee list and total repayment. If your basic needs depend on rolling over a previous loan, reconsider the borrowing decision.
- Calculate the net amount actually deposited
- Write down all fees and every due date
- Do not take a second app loan to repay the first without a plan
Worked App Comparison: The Amount On Screen Is Not The Money Received
Imagine a digital lender shows a Rs 20,000 loan but deducts charges before transferring money. The borrower must compare the cash received with the amount due, without treating this example as a quote from any particular app.
| Advertised principal | Rs 20,000 |
|---|---|
| Upfront deductions (hypothetical) | Rs 1,500 |
| Actual money transferred | Rs 18,500 |
| Total amount owed on due date | Rs 22,000 |
| Difference between repayment and cash received | Rs 3,500 |
What The Comparison Means Before You Act
- The illustrative Rs 3,500 cost is roughly 18.9% of the cash actually available, over the unspecified loan term; it is not an annual percentage rate.
- The borrowed money would have to cover a real expense and still be repaid by the written due date, including the entire Rs 22,000.
- Compare a competing offer on the same duration and net-disbursement basis, not on a headline Rs 20,000 figure alone.
- If deductions or costs are concealed until the final approval screen, save the offer and stop until the Key Facts Statement is understandable.
- Check if a rollover creates new charges and whether the lender reports payment performance to a credit bureau.
- After the price calculation, independently verify the exact app and operator on the newest SECP list before sharing your CNIC.
The example is deliberately simple: when short-term cost and repayment timing cannot be written on one page, the offer needs more scrutiny.
Illustrative worksheet: Figures are educational examples, not a real lender quotation or confirmed approval. Always use the responsible institution’s current written terms.
Two Realistic Loan Apps In Pakistan Situations
These scenarios are illustrations, not real applicants, case-law findings or promised outcomes. Their purpose is to show what a careful next decision looks like when one key detail is uncertain.
The App Advertises Rs 20,000 But Pays Rs 17,000
A user is offered Rs 20,000 principal while the transfer screen shows Rs 17,000 after deductions. They need the repayment total and due date before accepting; cost must be measured against actual cash received.
A “Collector” Threatens To Contact Relatives
A borrower is asked to share phone contacts after receiving a late notice. Save screenshots and transaction evidence, avoid new permissions, and complain through the lender’s official and appropriate regulatory process.
Choosing A Licensed App Or Safer Alternative
Loan applications differ by lender and programme. Follow the authorised current procedure, and separate application submission from credit approval and money being deposited.
- Name the exact product: Identify the licensed bank, NBFC or department responsible for loan apps in pakistan. Confirm its official portal or branch before providing information.
- Check whether it suits the purpose: Match the product’s geographic, age, income, security, tax and business-purpose rules to your situation, without assuming every lender has the same criteria.
- Calculate the real budget: Write down the expense that needs funding, money you can contribute, net cash required and the instalment that remains affordable in a weak month.
- Prepare truthful records: Make required identity, income, employment or business records consistent; do not pay an agent to alter credit or eligibility data.
- Apply through the proper channel: Use the verified online system or branch, save the acknowledgement and never share an OTP or PIN with a supposed loan officer.
- Read the offer before agreeing: Check the written amount, fees, net proceeds, repayment schedule, security, consent, default and complaints terms before signing or accepting digitally.
- Keep records after funding: Save the agreement, disbursement receipt, instalment record and lender contacts. If there is a problem, use the institution’s documented complaint process.
Official Loan Apps In Pakistan Sources And Independence
The links below are owned by the programme administrators or responsible public bodies. Their current instructions outrank summaries and old dates. SchemeInfo is an independent information publisher: it is not a government agency, bank, lending institution or government loan administrator.
Editorial review: 12 November 2026. Scheme rules and payments may change after this date. Verify before applying or sharing sensitive personal information.
Protect Your Phone, Data And Contacts
Digital lenders need identity and credit information, but permissions to read unrelated photos, personal contacts or entire device files deserve scrutiny. Read the privacy policy and consumer disclosure before granting access; decline a service that demands unnecessary access or threatens family members with collection messages.
Retain screen captures of the offer, repayment agreement, bank transfer and customer-support exchange. If you face harassment, unauthorised deductions or a data breach, report through the correct regulator and lawful complaint channel. Never send an OTP to an alleged agent who says they are repairing an account.
The safest outcome may be to use a bank, employer advance, trusted microfinance institution or a suitable subsidy programme rather than a high-cost short-term app.
- Limit permissions to a clear lending purpose
- Save the original agreement and repayment receipt
- Use SECP and official law-enforcement complaint routes for abuse
Official Sources And How To Verify Updates
Official programme notices and lender instructions take precedence over older articles, screenshots and social-media posts. Check the precise phase, date and applicant category before submitting personal details.
Related SchemesInfo Reading
For related topics, explore the following site searches. Each subject has its own rules and application procedure, so do not transfer eligibility requirements between programmes.