Online Loan In Pakistan: Find Regulated Lenders And Compare Real Costs
An online form can be convenient, but that does not make every app a licensed lender. Learn how to check the provider, read the contract, protect your phone and compare the amount received with the amount repayable.
The Short Answer
A responsible online application starts by identifying the regulated lender and reviewing every fee, repayment date and permission. Confirm the operator on an official register and avoid pressure to install unknown software or transfer activation money.
Programme Facts At A Glance
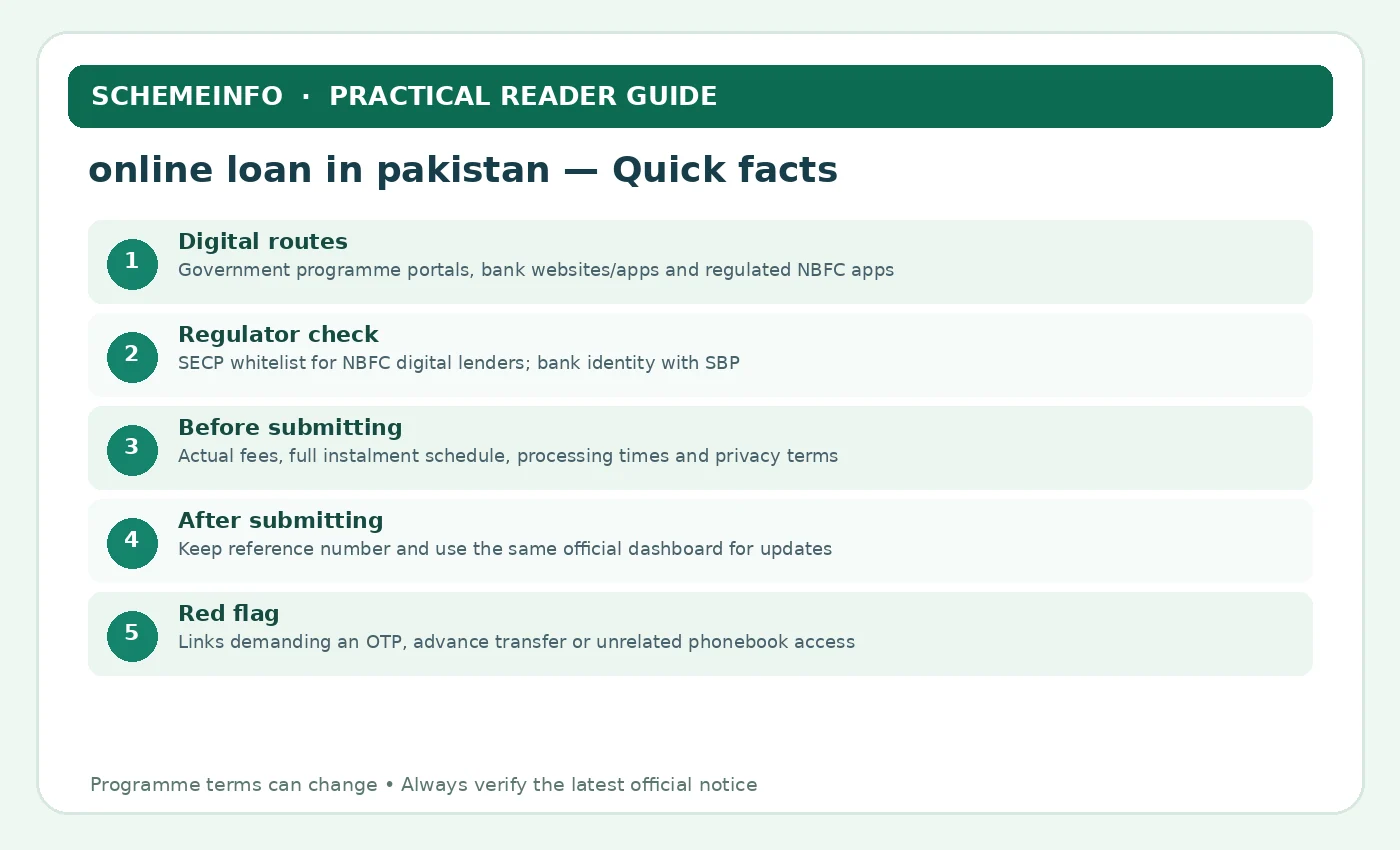
These are the central published facts for this programme, not a guarantee of admission, approval or an open registration window. The references at the bottom distinguish current official pages from historical phases.
| Digital routes | Government programme portals, bank websites/apps and regulated NBFC apps |
|---|---|
| Regulator check | SECP whitelist for NBFC digital lenders; bank identity with SBP |
| Before submitting | Actual fees, full instalment schedule, processing times and privacy terms |
| After submitting | Keep reference number and use the same official dashboard for updates |
| Red flag | Links demanding an OTP, advance transfer or unrelated phonebook access |
Lender Eligibility And Borrower Suitability
Begin with the responsible institution’s written eligibility rules for online loan in pakistan. These checks are not a promise of approval; eligibility is decided through the named programme’s actual verification process.
- Applicant meets the product’s actual age, CNIC, income, residence and credit-assessment conditions.
- Applicant uses a secure, authenticated website or licensed app and knows the legal entity behind it.
- Applicant has a reliable phone number and can complete lawful identity/biometric checks if required.
- Applicant can afford contractual repayments after living costs.
- Applicant understands that submitting an online request does not guarantee approval or same-day disbursement.
Document Checklist: Records And Proof
Keep essential records legible and separate from optional supporting papers. confirm which forms the responsible office requires before sharing identity or family information.
- Valid CNIC details submitted through a verified lender or programme portal.
- Applicant-owned mobile number and email address, if requested.
- Income information, bank statements or business details demanded by the specific provider.
- Bank or wallet account information only where required for authorised disbursement.
- Offer screen, contract, repayment schedule and application reference saved for follow-up.
- Do not provide passwords, private OTPs or unrestricted device access to unofficial representatives.
Verify The Legal Entity Behind The Phone App
Search results and sponsored social posts often identify a brand rather than the legal business providing the money. Before uploading identity documents, identify the operator, registration details and complaint address. For non-bank digital lenders, use the most recent SECP white list; for banking and microfinance-bank products, use the relevant institution and State Bank information.
A similarly named application may be unauthorised even if another product has a licence. Compare the full title, publisher and company name with the regulator record. A missing entry from a public blacklist does not establish approval. Record the list date so the guidance remains auditable when the list changes.
Where a lender links to a customer agreement only after installing the app, ask for the terms before granting permissions. Unclear terms are a reason to stop, not a reason to rush ahead.
- Verify the exact lender rather than the marketing brand
- Check app-store publisher and company contact details
- Keep copies of the quoted contract before consenting
How Regulated Digital Applications Are Evaluated
Use these programme-specific details to check the official route and to avoid interpreting a rule more broadly than it was written.
Online Application Is A Channel, Not A Loan Type
The phrase may describe an app-based nano loan, a bank’s digital application page or a provincial scheme portal. Those are fundamentally different products with different requirements. Before entering a CNIC, identify whether the site belongs to a bank, licensed NBFC or official government agency. If the purpose is a tractor subsidy, a commercial loan-app form is the wrong destination. an official bank or SECP reference is more valuable than sponsored ranking language.
Verify The Legal Lender And The Exact URL
Start from the company’s official site or the regulator’s list. For an NBFC loan app, compare the full name with SECP’s current whitelist; for bank credit, use the bank’s published domain. Look for fake spelling variants, shortened promotional links and social-media landing pages asking for payments. A padlock alone does not prove legitimacy, because fraudulent sites can also use HTTPS. A person considering online loan in pakistan should calculate monthly surplus using conservative figures.
How A Genuine Digital Application Usually Proceeds
A real lender may ask for basic identification, income, purpose and contact information, then verify the applicant and assess affordability. Only after checks does it present a final offer with charges and due dates. Some processes require branch confirmation or biometric verification. The fact that a screen says “submitted” should not be described as proof that a loan is approved. Under online loan in pakistan, the smallest advertised number is not automatically the cheapest loan.
Why Total Loan Cost Matters Online
Digital interfaces can focus attention on monthly instalments or the amount promised before showing deductions. Compare the money received with repayment totals including service charges, markup and any taxes or required insurance. For short terms, even a modest rupee charge can translate into a high effective financing cost. Do not accept a rushed offer without saving the full terms. In the context of online loan in pakistan, this difference can change both the applicant’s next action and expectations. Someone searching for online loan in pakistan might be under time pressure, which makes fake release charges particularly dangerous.
Digital Applications, Cost Disclosure And Privacy
CNIC Handling And Privacy Permissions
Identity documents must be shared carefully because a copied CNIC image can be misused. Use the authorised upload field, never an unrelated messaging account. Ask why the lender needs any access to contacts, files or location information and review the privacy policy. A request for a banking password or OTP through chat is not routine loan assessment. A credible guide to online loan in pakistan needs to acknowledge limits as clearly as the possible benefits. In assessing online loan in pakistan, the borrower should assume that a difficult month can happen.
Government Portal Versus Bank Or App
A public scheme might allow online registration but disburse funds through a separate partner bank or committee. Its deadlines and financing purpose are set by government rules. A private app typically assesses short-term individual credit under its own conditions. Read the source of funds, implementing organisation and authorised payment process rather than grouping all internet forms together. People researching online loan in pakistan should keep the original document date beside any figures they encounter. gather only the documents requested by a verified institution and keep copies of the versions submitted.
Comparing Offers With A Written Worksheet
Record provider name, type of regulation, principal, net disbursement, final repayment, number of instalments, due dates, penalties and complaint contact. Use exactly the same proposed principal when comparing offers. A form that never clearly reveals the cost is a reason to stop. A comparison worksheet is more useful than ranking providers by how frequently they appear in search results. Any decision involving online loan in pakistan is stronger when the applicant can show accurate records and a manageable budget. An enquiry about online loan in pakistan can end with a refusal or a smaller offer; that is not a reason to accept opaque charges.
What To Do If The Application Is Pending
Check the official application dashboard or contact the provider through its published number. Do not submit the same CNIC repeatedly through unfamiliar websites. Banks may need further employer or financial checks, and public programmes may pause intake while funds are allocated. Keep the reference number and date, then wait for the legitimate status update. The practical value of online loan in pakistan depends on the approved conditions, not the size of a headline. Where the search is online loan in pakistan, the correct product could be an asset loan, seasonal farm finance or a smaller livelihood facility rather than consumer cash.
Choosing The Right Borrowing Route
Beyond the headline amount, these details help a borrower compare the offer, prepare reliable evidence and avoid avoidable costs. Financial terms and availability always depend on the actual lender or programme.
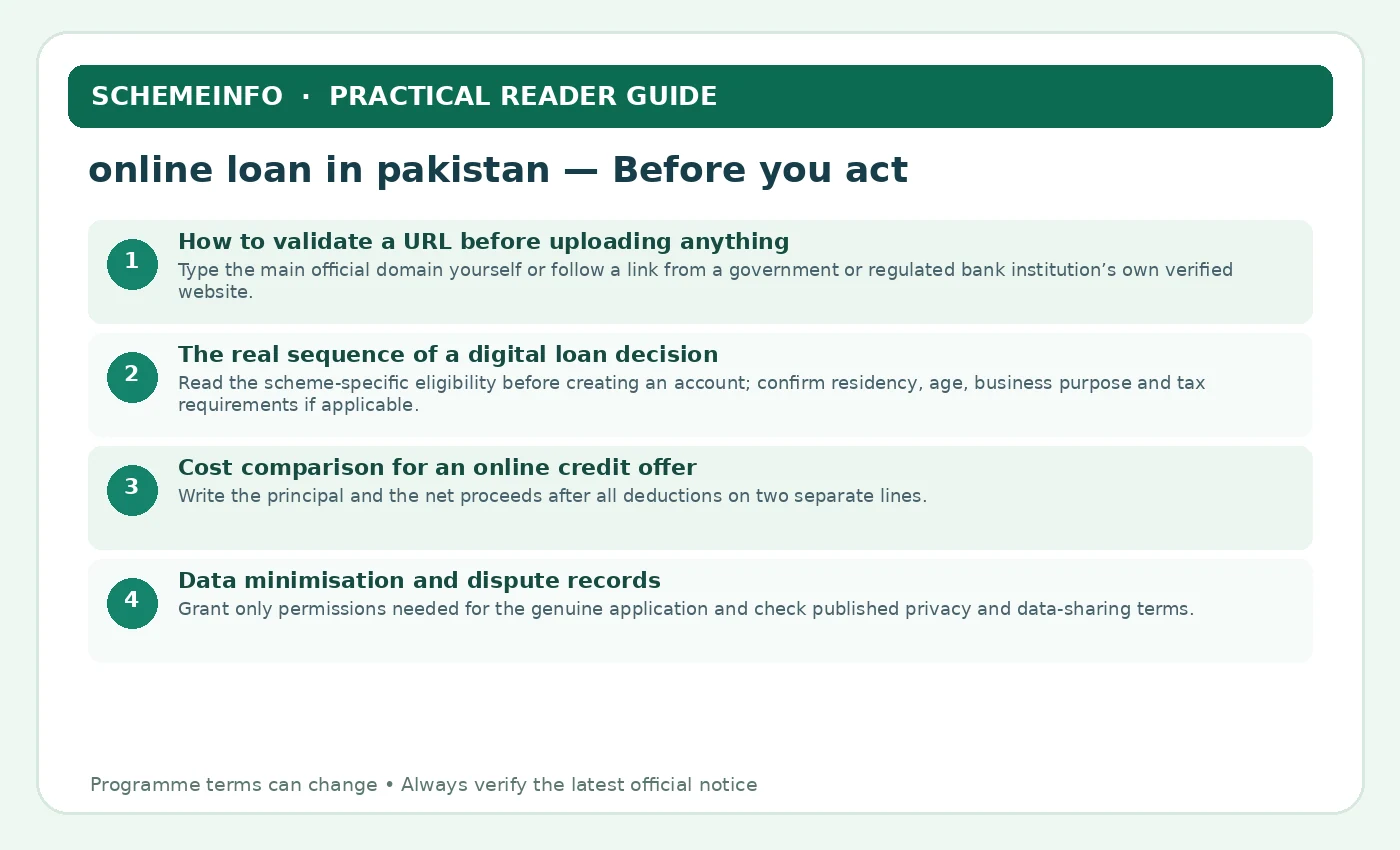
How To Validate A URL Before Uploading Anything
A genuine financial website can be imitated with one changed letter. Security should be checked before personal data is provided.
- Type the main official domain yourself or follow a link from a government or regulated bank institution’s own verified website.
- Check that the actual web domain matches the organisation, not just the logo, page title or HTTPS padlock.
- Do not trust results advertised as “priority application” when the proper programme portal is free or has a fixed published fee.
- Never enter an OTP, debit-card PIN, complete wallet password or bank-login credentials into an application-status page.
- Save the real help line and portal address locally so future status queries do not depend on old WhatsApp forwards.
A page can be professionally designed and still fraudulent. Trust comes from the verified source, not the graphics.
The Real Sequence Of A Digital Loan Decision
Form submission, document validation, underwriting, formal sanction and disbursement are distinct stages. Keeping them separate prevents unrealistic expectations.
- Read the scheme-specific eligibility before creating an account; confirm residency, age, business purpose and tax requirements if applicable.
- Enter the exact CNIC and mobile details you control and check names against bank and identity records.
- Upload legible evidence in the requested file format; do not modify records to satisfy an unknown agent.
- After submission, save the acknowledgement and use the portal’s official tracking function or branch support for later stages.
- Never treat “submitted” or “shortlisted” as permission to spend against a loan that has not been contracted and disbursed.
The safest online application is an auditable sequence, not the fastest collection of documents.
Compare What Enters Your Account With What Leaves It
Suppose an advertised Rs 30,000 facility deducts Rs 3,000 in fees and requires repayment of Rs 33,000 after one month. The cash actually received is Rs 27,000, while the repayment obligation is Rs 33,000. The Rs 6,000 difference in a short period is more informative than a vague “low rate” badge.
Prepare a comparison on a consistent basis: cash deposited, every fee deducted or added, due dates, late charges, early-settlement terms and any changes after renewal. Convert “service fees” into the overall amount that must be repaid; they can materially change the cost.
For wage earners, compare the repayment date with pay-day rather than relying on a calendar month. For seasonal or self-employed borrowers, check whether the loan matures before the income event expected to repay it.
- Write down the net disbursement and total contractual repayment
- Compare offers on the same dates and cash amount
- Avoid rollover plans that depend on taking another instant loan
Practical Risk And Application Checks
Beyond the headline amount, these details help a borrower compare the offer, prepare reliable evidence and avoid avoidable costs. Financial terms and availability always depend on the actual lender or programme.
Cost Comparison For An Online Credit Offer
Digital convenience does not remove the need to compare money received, money repaid and due dates. Ask the lender to disclose the full offer.
- Write the principal and the net proceeds after all deductions on two separate lines.
- Calculate total rupees due over the agreed term, including known charges and any mandatory add-ons.
- Check the first instalment date against confirmed income rather than assuming a loan will be repaid from future borrowing.
- Assess variable pricing, rollovers and late penalties, particularly on short-term nano lending.
- Keep a secure copy of terms and a payment receipt so an incorrect balance can be challenged later.
No applicant should accept a binding loan offer merely because a countdown timer appears on a phone screen.
Data Minimisation And Dispute Records
A lender can legitimately verify identity without collecting unrelated personal information. Protecting evidence is also important if something goes wrong.
- Grant only permissions needed for the genuine application and check published privacy and data-sharing terms.
- Refuse demands to hand over unrelated family contacts or full photo galleries as a condition of a cash transfer.
- Keep a timestamped copy of any suspicious request, unauthorised charge or disagreement about a repayment.
- Use the official lender complaint channel and then the appropriate regulator based on whether the lender is a bank or NBFC.
- Change credentials and seek official account help promptly if financial passwords or OTPs were exposed.
If a website cannot identify the responsible institution and a written complaints route, it is not a safe place for identity documents.
Worked Online Offer: Three Screens That Must Agree
A digital loan application can show a headline amount, a net disbursement screen and a later repayment agreement. These numbers should reconcile before any electronic acceptance. The following hypothetical transaction illustrates what to check.
| Headline loan amount | Rs 40,000 |
|---|---|
| Deductions displayed before transfer | Rs 3,500 |
| Cash reaching the bank account | Rs 36,500 |
| Total repayment requested | Rs 44,000 |
| Total difference from usable cash | Rs 7,500 |
What The Comparison Means Before You Act
- The hypothetical difference is about 20.5% of actual cash received over the example term; no annual rate is inferred without a specific duration.
- Ask which line items make up Rs 3,500 in deductions and whether the repayment includes additional profit, interest or other fees.
- If the advertised site and final offer identify different legal companies, pause and independently check the operator.
- Save the agreement and reference number before accepting, then compare the credited amount with the bank statement.
- Never approve an unexpected OTP request from a caller who claims to “speed up verification”.
- If the funds or repayment figures are wrong, raise a documented complaint through the institution’s real channel.
The online channel should make the transaction clearer and more traceable, not remove the borrower’s right to understand the obligation.
Illustrative worksheet: Figures are educational examples, not a real lender quotation or confirmed approval. Always use the responsible institution’s current written terms.
Two Realistic Online Loan In Pakistan Situations
These scenarios are illustrations, not real applicants, case-law findings or promised outcomes. Their purpose is to show what a careful next decision looks like when one key detail is uncertain.
A Portal Redirects To An Unknown Messenger Account
A borrower starts on a copied “government” landing page, then is asked to message documents to a private number. They should stop and manually visit the department’s verified domain.
A Legitimate Application Says “Under Review”
An applicant resubmits three times because there is no SMS. Better to check the original tracking reference and published contact channel, then ask for a reasoned status update without duplicate filings.
Your Next Steps
Loan applications differ by lender and programme. Follow the authorised current procedure, and separate application submission from credit approval and money being deposited.
- Name the exact product: Identify the licensed bank, NBFC or department responsible for online loan in pakistan. Confirm its official portal or branch before providing information.
- Check whether it suits the purpose: Match the product’s geographic, age, income, security, tax and business-purpose rules to your situation, without assuming every lender has the same criteria.
- Calculate the real budget: Write down the expense that needs funding, money you can contribute, net cash required and the instalment that remains affordable in a weak month.
- Prepare truthful records: Make required identity, income, employment or business records consistent; do not pay an agent to alter credit or eligibility data.
- Apply through the proper channel: Use the verified online system or branch, save the acknowledgement and never share an OTP or PIN with a supposed loan officer.
- Read the offer before agreeing: Check the written amount, fees, net proceeds, repayment schedule, security, consent, default and complaints terms before signing or accepting digitally.
- Keep records after funding: Save the agreement, disbursement receipt, instalment record and lender contacts. If there is a problem, use the institution’s documented complaint process.
Defend Your Personal Data And Respond To Harassment
A borrower’s CNIC and contact details are sensitive. An app should explain why it needs any device permission and how data will be stored, shared and deleted. Requests for unrelated gallery access, entire contact lists or passwords should trigger further scrutiny.
Save the approval screen, contract, debit instructions and repayment receipts. If collectors threaten to contact relatives, disclose personal information or demand funds outside the written contract, document the conduct and use the lender’s complaint function and the appropriate regulator channel.
If you have already installed a suspicious app, revoke unnecessary permissions, update passwords through official channels, alert your payment provider to questionable instructions and seek competent consumer or law-enforcement assistance where needed.
- Protect OTPs, passwords and full phone-book access
- Save repayment receipts and communications
- Complain through regulator or official provider channels
Official Sources And How To Verify Updates
Official programme notices and lender instructions take precedence over older articles, screenshots and social-media posts. Check the precise phase, date and applicant category before submitting personal details.
Related SchemesInfo Reading
For related topics, explore the following site searches. Each subject has its own rules and application procedure, so do not transfer eligibility requirements between programmes.