Bank Loan In Pakistan: Practical Eligibility, Costs, Verification And Next Steps
Choosing a bank loan in Pakistan should start with the purpose and the total contractual cost, not a headline “instant approval” claim. This guide explains the main product categories, documents, credit decisions and what to ask before signing.
The short answer
Banks assess financing according to product type, verified income, existing obligations, credit history and security where relevant. Consumer, SME and housing financing follow different regulatory frameworks. Advertised pre-qualification is not the same as a bank’s signed approval.
Current Official Position And What It Means
Our review uses the official programme information available on 15 November 2026. A webpage can describe a product without confirming whether applications are being accepted in every district, whether funds are available, or what an individual household will receive. Always distinguish published policy from a personal approval.
| Question | Evidence-based answer |
|---|---|
| What are you evaluating? | bank loan in pakistan |
| Where should details be checked? | Official programme information |
| What must not be assumed? | That an application, assessment, approval and payment are the same stage. |
Read The Real Cost In One Comparison Sheet
Ask each lender for the annual rate or profit structure, whether it can change, the full repayment schedule, processing charges, insurance or takaful cost, collateral charges, late-payment terms and early-settlement conditions. Compare offers over the same amount and period. Otherwise a low monthly instalment can conceal a much longer repayment obligation.
For a hypothetical Rs 500,000 facility, a borrower might see two quotes with different monthly payments because one lasts 24 months and the other 48 months. The second quote may ease monthly pressure but produce a larger total repayment. Add up every instalment and every known fee before comparing.
Distinguish conventional interest, Islamic financing arrangements and government-subsidised products. They can have different contracts, price-setting methods and ownership structures. The appropriate comparison is what the customer must pay, what rights arise under the contract and what happens on default.
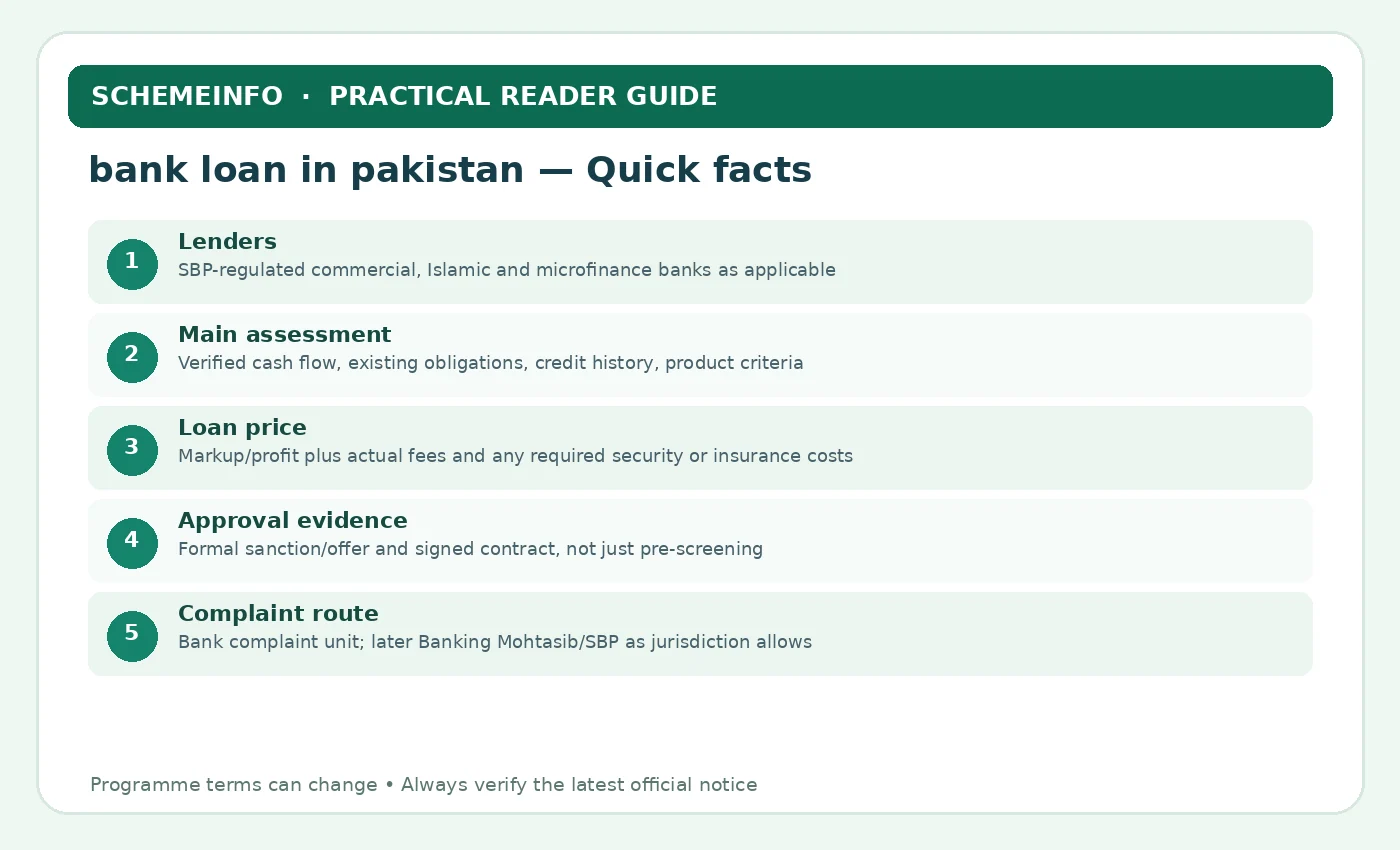
Key Facts At A Glance
These are the central published facts for this programme, not a guarantee of admission, approval or an open registration window. The references at the bottom distinguish current official pages from historical phases.
| Lenders | SBP-regulated commercial, Islamic and microfinance banks as applicable |
|---|---|
| Main assessment | Verified cash flow, existing obligations, credit history, product criteria |
| Loan price | Markup/profit plus actual fees and any required security or insurance costs |
| Approval evidence | Formal sanction/offer and signed contract, not just pre-screening |
| Complaint route | Bank complaint unit; later Banking Mohtasib/SBP as jurisdiction allows |
Lender Eligibility And Borrower Suitability
Begin with the responsible institution’s written eligibility rules for bank loan in pakistan. These checks are not a promise of approval; eligibility is decided through the named programme’s actual verification process.
- Applicant meets the chosen bank’s minimum age, residency, KYC and legal eligibility conditions.
- Applicant has verifiable salary, business receipts or other acceptable income for the proposed instalment.
- Applicant’s existing debts and credit profile are acceptable under bank assessment.
- Applicant meets product-specific conditions for employment tenure, business history or collateral where applicable.
- Applicant provides genuine ownership, supplier or asset records for secured financing.
- Applicant can sign the bank’s complete terms and understand variable-rate and late-payment clauses.
Proof Of Identity And Supporting Documents
Keep essential records legible and separate from optional supporting papers. For bank loan in pakistan, confirm which forms the responsible office requires before sharing identity or family information.
- Valid CNIC and updated address/contact information.
- Recent salary slips or employer certificate for salaried applicants, as requested.
- Bank statements over the period specified by the selected bank.
- Business accounts, tax evidence or invoices where the borrower is self-employed.
- Property title, vehicle quotation or other security documents if the loan is asset-backed.
- Existing borrowing declarations and credit consent where required by the bank.
How The Programme Works In Practice
Use these programme-specific details to check the official route and to avoid interpreting a rule more broadly than it was written.
Choose A Bank Product, Not Just A Headline Loan
A bank may offer separate salary-based personal finance, vehicle finance, housing finance and working-capital credit. These products differ in collateral, maturity and pricing. An applicant asking for shop inventory should not automatically choose a long-term consumer facility, just as a borrower planning a house should not rely on a tiny short-term mobile loan. For bank loan in pakistan, an official bank or SECP reference is more valuable than sponsored ranking language.
How Banks Assess Repayment Capacity
Banks examine more than the salary printed on one slip. They consider stable take-home earnings, existing instalments, household costs, employment or business history and credit information. A bank that offers a high maximum principal will still decline an unsuitable case. Calculate a conservative repayment budget before applying, and leave room for medical, rent and school expenses. A person considering bank loan in pakistan should calculate monthly surplus using conservative figures.
Salaried Applicants And Employer Evidence
Employees usually need consistent identification, salary records and evidence that their income arrives regularly. Some banks favour salary accounts held with the same institution, but this is not universal. Contract, probationary and commission-based income may be assessed differently. Check the lender’s actual requirements rather than copying an eligibility list from a competitor’s website. Under bank loan in pakistan, the smallest advertised number is not automatically the cheapest loan.
Self-Employed Business Records
A self-employed applicant may need transactions, sales ledgers, tax records and business continuity evidence. A busy shop does not automatically prove sufficient net earnings: rent, inventory replacement, transport and wages must be deducted. Seasonal businesses should use several months of data. Honest evidence may support a smaller, more sustainable facility. In the context of bank loan in pakistan, this difference can change both the applicant’s next action and expectations. Someone searching for bank loan in pakistan might be under time pressure, which makes fake release charges particularly dangerous.
Income Evidence, Charges And Security
Fixed Versus Variable Pricing
A payment may be fixed throughout the agreed period or linked to a reference benchmark at later dates. Housing and business finance can have pricing structures that reset, while certain subsidised schemes have an initial fixed period. Ask for sample instalments under plausible rate changes. Understanding the reset clause protects a household from surprises several years after signing. A credible guide to bank loan in pakistan needs to acknowledge limits as clearly as the possible benefits. In assessing bank loan in pakistan, the borrower should assume that a difficult month can happen.
Collateral And Legal Ownership
Secured facilities can require title verification, valuation, insurance and enforceable bank charges over property or equipment. These conditions add time and costs even when the quoted financing rate looks attractive. A property still under inheritance dispute or missing proper registration may not be acceptable security. Clarify the legal requirements before paying for reports. People researching bank loan in pakistan should keep the original document date beside any figures they encounter. For bank loan in pakistan, gather only the documents requested by a verified institution and keep copies of the versions submitted.
Total Fees And Repayment Schedule
Add processing fees, documentation, valuation, takaful or insurance, account charges and any lawful taxes to the total price. Check whether instalments are monthly, quarterly or linked to seasonal receipts. Read early settlement and missed-payment clauses carefully. The amount of cash that reaches your account may be lower than the nominal approved principal. Any decision involving bank loan in pakistan is stronger when the applicant can show accurate records and a manageable budget. An enquiry about bank loan in pakistan can end with a refusal or a smaller offer; that is not a reason to accept opaque charges.
Pre-Qualification Is Not Final Approval
A call-centre estimate or web calculator may tell an applicant that a certain amount appears possible. The bank still needs documented underwriting, compliance checks and contract acceptance. Never pay a third party for a supposed approval letter. A genuine decision should come through the regulated bank’s identifiable channel and be backed by written terms. The practical value of bank loan in pakistan depends on the approved conditions, not the size of a headline. Where the search is bank loan in pakistan, the correct product could be an asset loan, seasonal farm finance or a smaller livelihood facility rather than consumer cash.
Which Situation Fits You? A Practical Comparison
Similar searches often hide very different needs. Use these examples to decide which documents, questions and programme conditions matter to you.
Build a disposable-income worksheet and compare all fees.
Prepare transaction-backed records rather than only a verbal income figure.
Check security/title and the specific housing-finance rules separately.
These scenarios are illustrative rather than eligibility decisions. The relevant authority or lender must confirm each actual case using current rules and documentary evidence.
Protect Your Borrowing Record And Your Ability To Complain
Keep copies of the Key Facts Statement, signed finance agreement, security documents, repayment schedule and fee disclosure. Report an unexpected debit or misleading sales claim promptly through the bank’s complaints channel. If the bank’s response is unsatisfactory, use the relevant escalation process under current State Bank and Banking Mohtasib guidance.
Never tell an agent your banking OTP or let them complete the application using a different mobile number. If someone asks for a “guaranteed approval charge” in a personal wallet, stop and verify directly with the institution.
Treat a rejection as a prompt to check credit-report accuracy, current debt obligations and missing documents. Repeated rushed applications can create unnecessary enquiries without resolving the underlying reason.
Costs, Documents And Decisions
Conventional And Islamic Bank Structures
Islamic banks may use diminishing musharakah, murabaha or other approved structures, depending on the product. They are not interchangeable with an interest-free grant. Ask for the schedule of rentals or profit, ownership obligations, insurance, late-payment treatment and early settlement. Comparison is easiest when total cost and obligations are shown alongside conventional offers. A family comparing bank loan in pakistan should look at personal eligibility before relying on publicised amounts. Before continuing with bank loan in pakistan, confirm both the website and the operator, and avoid installing remote-control software at a stranger’s request.
Documents That Create Delays
Common avoidable problems include expired CNIC data, mismatched spellings, incomplete salary history, undocumented cash sales and missing property papers. It is better to ask for a checklist early than to submit an incomplete application repeatedly. Keep a copy of every document shared and use secure bank channels rather than informal messaging groups. If the details of bank loan in pakistan are disputed, ask the responsible office for its current written explanation. When tracking bank loan in pakistan, rely on a formal status reference.
If A Bank Charges Wrongly Or Mishandles A Case
SBP tells consumers to approach the bank’s complaint-management unit first, then use appropriate escalation channels. Preserve payment receipts, the signed schedule, correspondence and dates. Explain the precise transaction or contract clause in dispute. Complaints can address service problems, but they do not replace credit underwriting or compel the institution to approve an unaffordable application. A person using bank loan in pakistan should avoid funding one instalment with another high-cost loan.
Choosing The Right Borrowing Route
Beyond the headline amount, these details help a borrower compare the offer, prepare reliable evidence and avoid avoidable costs. Financial terms and availability always depend on the actual lender or programme.
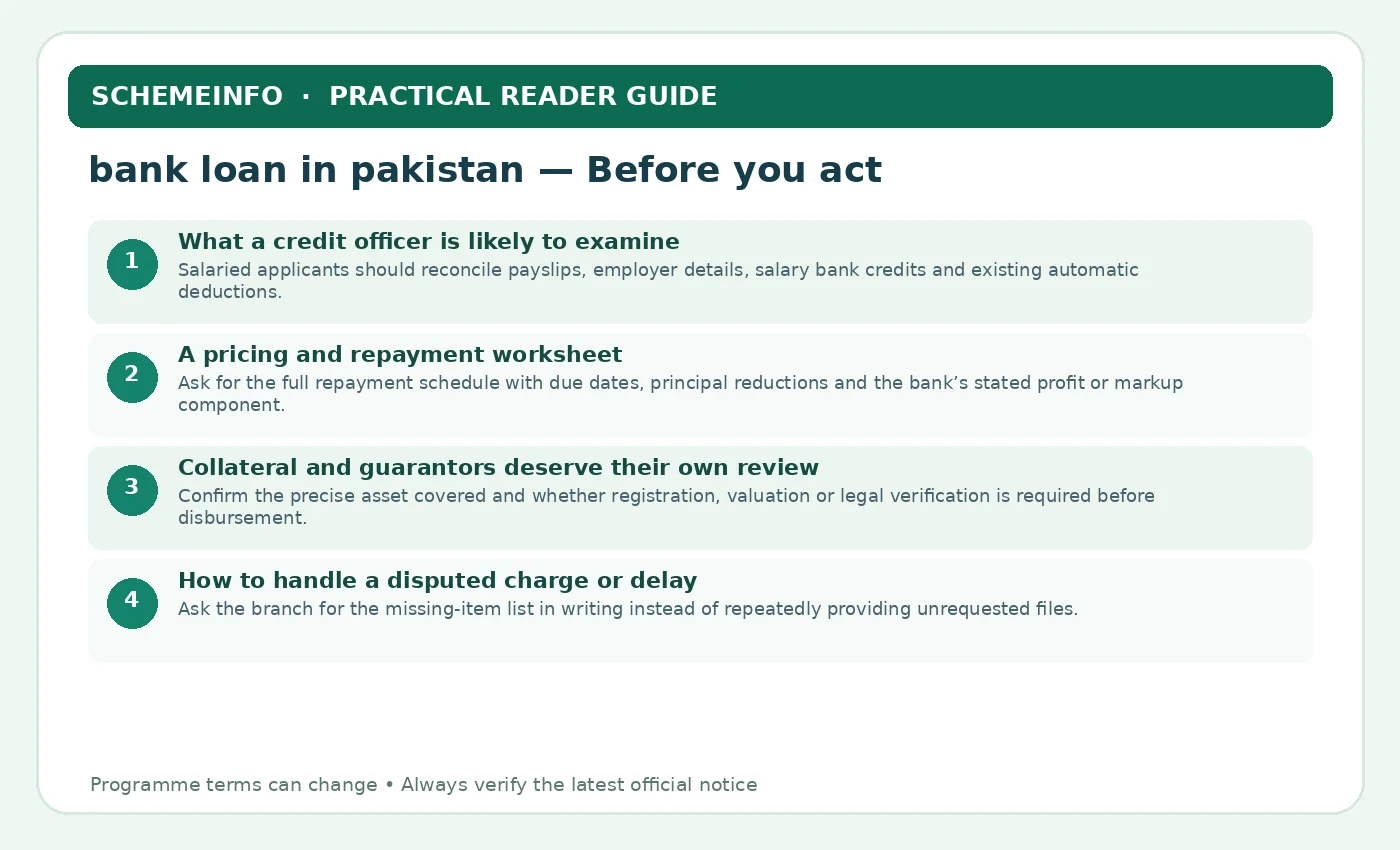
What A Credit Officer Is Likely To Examine
Banks need evidence that repayment can continue, not simply an applicant’s estimated salary. The specific documents depend on the bank and product.
- Salaried applicants should reconcile payslips, employer details, salary bank credits and existing automatic deductions.
- Self-employed applicants should reconcile customer receipts, business-account credits, invoices, cash expenses and income-tax records.
- Large occasional transfers may be questioned; note whether they are business revenue, family assistance or one-time asset sales.
- A clean property title does not replace the borrower’s ability to meet scheduled payments, even when collateral is offered.
- Prepare clear responses to discrepancies in CNIC spelling, contact details, employment dates and banking statements.
Documentation should tell one consistent financial story instead of displaying the highest available amount.
A Pricing And Repayment Worksheet
Borrowers often ask only for the monthly instalment. A safer test considers total lifetime payment, how the rate is calculated and what happens when circumstances change.
- Ask for the full repayment schedule with due dates, principal reductions and the bank’s stated profit or markup component.
- Check whether variable pricing can move with a benchmark and whether your budget could tolerate a higher instalment.
- List one-time legal, processing, appraisal, insurance and security-release charges separately from periodic payments.
- Understand the consequences of settlement before the end of term, including any notice or early-settlement costs.
- Compare the net usable proceeds with all contracted repayments; exclude promotional amounts that are not actually disbursed.
Put all offers on the same time basis before comparing a fixed three-year arrangement with a five-year variable facility.
Borrowing Risks And Common Application Mistakes
Collateral And Guarantors Deserve Their Own Review
The security package may be more consequential than the advertised markup. It can affect family assets and other people.
- Confirm the precise asset covered and whether registration, valuation or legal verification is required before disbursement.
- Ask which events count as default and how much written notice the bank must provide under the contract and applicable law.
- If a guarantor is involved, explain that signature is a possible repayment obligation, not merely a character reference.
- Keep photocopies of all signed deeds, guarantees, original-document receipts and releases.
- After final repayment, request a documented no-dues status and the release or cancellation of any registered security.
Do not sign blank forms or surrender original property papers without official acknowledgement and a verifiable transaction.
How To Handle A Disputed Charge Or Delay
A delay can result from missing evidence, internal underwriting or an error. Treat each problem according to its actual cause.
- Ask the branch for the missing-item list in writing instead of repeatedly providing unrequested files.
- If an approved fee differs from the published schedule, preserve the offer, receipt and communications and request reconciliation.
- Use the bank’s complaint management unit first; save the complaint reference and dates.
- SBP’s Sunwai guidance describes Banking Mohtasib escalation after an unsatisfactory response or the applicable time threshold.
- Do not assume every institution falls under the same ombudsman: microfinance and NBFC complaint paths may differ.
An evidence-based complaint with a clear remedy requested is easier to resolve than a general statement that the bank behaved unfairly.
Borrower Decision Worksheet: Bank Loan In Pakistan
For bank loan in pakistan, work through these questions before providing personal records or accepting a financing offer. This is an independent decision tool, not a lender application form. Write the evidence or published rule that answers each question.
- Decision 1: Which named lender, department or licensed company would make the actual decision?
- Decision 2: Is this the currently authorised application route, and what date is the guidance from?
- Decision 3: What amount would reach my account after processing and other authorised deductions?
- Decision 4: What exact dates and amounts would I repay, including any compulsory fees?
- Decision 5: How much remains after rent, food, utilities, transport and all existing repayments?
- Decision 6: What happens to collateral, guarantors or credit records if I miss a payment?
- Decision 7: Can I prove the spending purpose and funds use with appropriate business or personal records?
- Decision 8: Where is the responsible organisation’s official complaints and correction channel?
Four Checks Specific To This Financing Question
Prepare clear responses to discrepancies in CNIC spelling, contact details, employment dates and banking statements.
Compare the net usable proceeds with all contracted repayments; exclude promotional amounts that are not actually disbursed.
After final repayment, request a documented no-dues status and the release or cancellation of any registered security.
Do not assume every institution falls under the same ombudsman: microfinance and NBFC complaint paths may differ.
The purpose of a worksheet is to prevent one misleading number from deciding the entire choice. Compare the original source, the actual offer and the household budget. If any one of these is missing, the sensible next action is further verification rather than signing.
Worked Bank Scenario: A Debt Burden Test Needs Two Income Levels
Consider an employed borrower comparing a new instalment against current household costs. An apparently affordable monthly payment may become difficult after overtime, commission or business income drops. The figures below are an illustration, not an SBP regulatory debt-burden threshold.
| Ordinary monthly take-home pay | Rs 125,000 |
|---|---|
| Necessary household spending | Rs 75,000 |
| Existing debt repayments | Rs 20,000 |
| Available before a new loan | Rs 30,000 |
| Balance after a Rs 24,000 new instalment | Rs 6,000 |
What The Comparison Means Before You Act
- The initial Rs 6,000 cushion is small relative to the scale of the payment, particularly when irregular costs are not yet included.
- If income falls 20% to Rs 100,000 while expenses remain unchanged, the current Rs 20,000 debt leaves only Rs 5,000 before the proposed instalment.
- Ask whether the price is fixed or variable and how much the repayment would change under the written terms.
- A security asset might help the bank evaluate risk but does not create cash for the borrower to make monthly payments.
- Use bank statements and verified payslips to estimate sustainable income instead of including uncertain future bonuses.
- If the downside case is unmanageable, request a smaller loan, longer preparation period or a non-borrowing alternative.
The lending bank applies its own qualifying rules; the borrower should conduct a stricter personal budget test alongside them.
Illustrative worksheet: Figures are educational examples, not a real lender quotation or confirmed approval. Always use the responsible institution’s current written terms.
Two Realistic Bank Loan In Pakistan Situations
These scenarios are illustrations, not real applicants, case-law findings or promised outcomes. Their purpose is to show what a careful next decision looks like when one key detail is uncertain.
Salary Is Regular But Other Debts Are Heavy
A salaried employee has stable pay but multiple instalments. They should calculate verified remaining income after all obligations and test the proposed payment against household essentials.
Shop Earnings Are Strong Only In One Season
A business owner presents three good months but little evidence for the rest of the year. Better records showing twelve-month deposits, costs and tax history help both lender and borrower assess the risk.
How To Proceed With Bank Loan In Pakistan
Loan applications differ by lender and programme. Follow the authorised current procedure, and separate application submission from credit approval and money being deposited.
- Name the exact product: Identify the licensed bank, NBFC or department responsible for bank loan in pakistan. Confirm its official portal or branch before providing information.
- Check whether it suits the purpose: Match the product’s geographic, age, income, security, tax and business-purpose rules to your situation, without assuming every lender has the same criteria.
- Calculate the real budget: Write down the expense that needs funding, money you can contribute, net cash required and the instalment that remains affordable in a weak month.
- Prepare truthful records: Make required identity, income, employment or business records consistent; do not pay an agent to alter credit or eligibility data.
- Apply through the proper channel: Use the verified online system or branch, save the acknowledgement and never share an OTP or PIN with a supposed loan officer.
- Read the offer before agreeing: Check the written amount, fees, net proceeds, repayment schedule, security, consent, default and complaints terms before signing or accepting digitally.
- Keep records after funding: Save the agreement, disbursement receipt, instalment record and lender contacts. If there is a problem, use the institution’s documented complaint process.
Practical Checklist: Verify, Prepare, Compare And Follow Up
Use this short workflow before relying on a claim in a video, broker message or outdated article. It is useful whether you are submitting an application, comparing finance or tracking an existing benefit.
- Identify the programme precisely. Check the official name, relevant agency and product type.
- Read current eligibility. Match the district, family circumstances, age and documents to the published requirements.
- Verify the official route. Type the authority’s web address yourself or use its published branch details.
- Estimate costs and time. Include fees, travel, waiting periods, instalments or conditional visits as relevant.
- Keep a document record. Save the reference number, receipts and any written answer from staff.
- Protect your identity. Never disclose an OTP or pay to a personal wallet for “guaranteed” approval.
- Check the next stage. Registration is not selection; selection is not necessarily disbursement.
- Follow up through official channels. Escalate a rejected, delayed or incorrect record using the published complaints process.
Official Sources And Editorial Notes
Primary government, regulator or programme-provider references are listed below. The guide is independent and does not accept applications, collect CNIC information or guarantee approval. Some pages display historic scheme parameters; check the date and the most recent notice.
Research review: 15 November 2026. Product terms, public-service operations, eligibility, coverage and fees may change. Worked figures in this article are explanations, not offers or guaranteed payments.
Frequently Asked Questions
What Document Is Usually Needed First?
A valid CNIC and the selected bank’s required identification data.
Do Banks Always Ask For Salary Slips?
Requirements depend on employment status and product; business borrowers may use other evidence.
Is Collateral Compulsory?
No. It varies between secured and unsecured products.
Can A Bank Refuse A Loan Despite Strong Income?
Yes. It may consider existing obligations, credit history or other risk criteria.
Can Bank Terms Change Later?
Variable-rate products may have contractually defined resets.
Does An Online Calculator Mean Approval?
No. It is a preliminary estimate.
Is Islamic Bank Finance Free?
Not necessarily; it can use contractual profit or rental arrangements.
Should I Compare Fees?
Yes. Fees and total repayments can materially change the cost.
What If An Instalment Is Missed?
Contact the bank immediately and review the contractual consequences.
Where Can I Complain?
Start with the bank complaint unit and follow applicable SBP escalation guidance.