Explore the difference between Punjab’s two Asaan Karobar Finance tiers, including tax requirements, personal guarantees, secured lending, loan uses and the budget checks a business owner should do first.
Table of Contents — jump to a section
- How the financing works in practice
- Verified facts at a glance (November 2026)
- What the updated rules mean in practice
- How Asaan Karobar Finance works in practice
- Eligibility for Asaan Karobar Finance: who should check first
- Limits, fees and the practical budget
- Documents for Asaan Karobar Finance
- How to use Asaan Karobar Finance through official channels
- Common application situations and how to respond
- Mistakes that cost applicants time or money
- Choose the correct Asaan Karobar Finance tier
- Make the numbers support the application
- Prevent delays and avoid expensive misunderstandings
- A finance-tier decision exercise
- A practical pre-application checklist
- Three applicant situations: what to do next
- Explore related Scheme Info guides
- Frequently asked questions
- Official sources and editorial disclosure
How the financing works in practice
A larger SME loan can make sense for an established business, but it also needs documented cash flow and careful review of fees. This guide separates the published Punjab rules from questions that only a lender can resolve.
Asaan Karobar Finance targets small and medium businesses located in Punjab. It is intended for ventures that need capital for establishment, expansion, modernisation, operating finance, commercial logistics or approved climate-friendly improvements. It is a different programme from the lower-limit Asaan Karobar Card.
An applicant should first decide which business expense is being financed. A specific requirement, supplier quote or credible expansion plan is easier to assess than an unexplained request for the maximum financing available.
SME classifications and business-size tests may affect which tier is suitable. Review the official requirements rather than assuming every registered business qualifies.
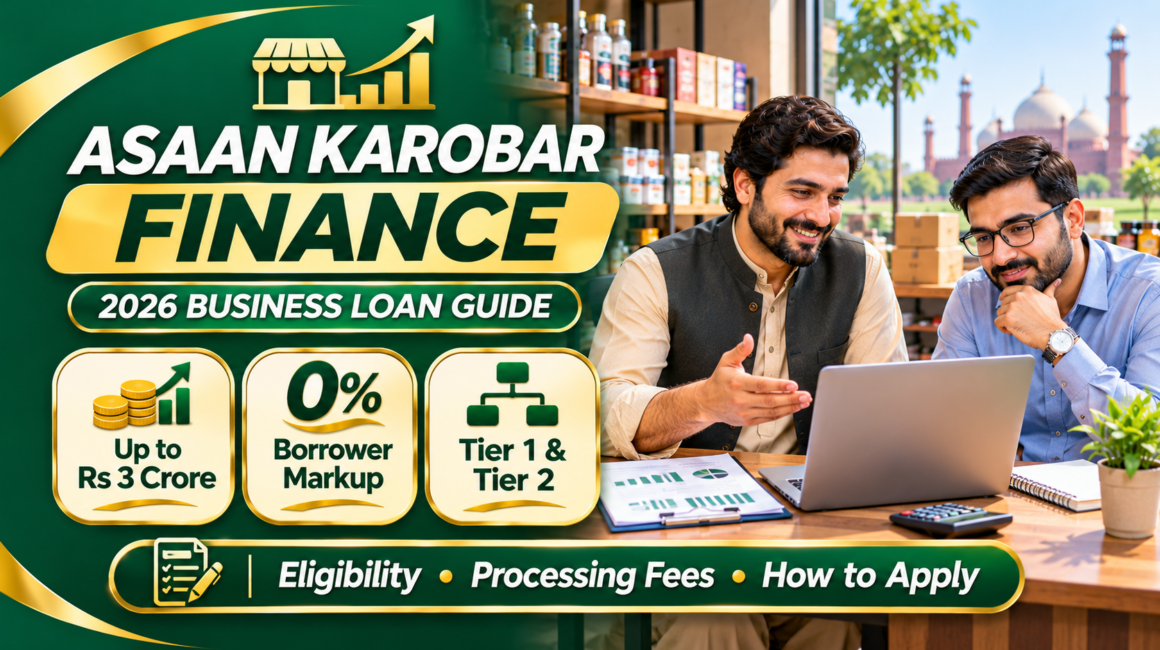
The Government of Punjab describes Tier 1 financing of approximately PKR 1 million to 5 million on personal-guarantee terms and Tier 2 secured financing of higher amounts up to PKR 30 million. The published customer markup rate is 0%, with repayment periods of up to five years.
The provincial overview lists processing fees of PKR 5,000 for Tier 1 and PKR 10,000 for Tier 2, alongside possible handling charges, insurance, legal and registration expenses. It also explains equity contributions for some cases. Do not rely on the zero-markup label alone when calculating the total cost.
For programme support, the Punjab overview lists helpline 1786. Confirm this contact number against the official website before calling.
The Asaan Karobar Card has a smaller maximum limit and structured day-to-day digital business spending. Asaan Karobar Finance is aimed at larger SME needs and places greater emphasis on tax status, documented premises, project viability and tier-specific security. A business should compare both the permitted purpose and all applicable costs before choosing a path.
For this particular question, Asaan Karobar Finance should be judged against the official policy rather than a generic financing advertisement.
Verified facts at a glance (November 2026)
These are published official rules, programme targets or procedural details. They are not a personal eligibility determination, a live-registration claim or an approval promise.
| Question | Official detail or important distinction |
|---|---|
| Tier 1 | Rs 1–5 million, personal guarantees, up to five-year repayment, published 0% end-user rate. |
| Tier 2 | More than Rs 5 million up to Rs 30 million, security/collateral, up to five-year repayment, published 0% end-user rate. |
| Age | 25–55 years on the application date. |
| Tax registration | Valid NTN and active filer status under Punjab Portal guidance. |
| Credit profile | Clean credit history, Punjab resident and business located in Punjab. |
| Application processing fee | Published Rs 5,000 Tier 1 and Rs 10,000 Tier 2. |
| Grace period | Up to six months for new businesses, up to three months for existing enterprises, under public programme descriptions. |
| Important distinction | Interest-free pricing does not waive processing, documentation, collateral or normal financial obligations. |
What the updated rules mean in practice
Choose between the unsecured and secured tier
Asaan Karobar Finance has a different structure from the digital Asaan Karobar Card. The Punjab government describes Tier 1 at Rs 1–5 million with a personal guarantee and Tier 2 for larger, secured financing up to Rs 30 million. The presence of collateral may affect the scope of valuation, legal work and lender checks. An applicant should not request a larger secured facility simply because the headline customer interest rate is shown as zero.
Turn a business plan into bank-ready evidence
Prepare a plain-language summary of the business model, how much capital is needed, which costs will be paid and when the financed investment should generate cash. A manufacturing business might need quotations for a machine, expected production hours, raw material purchases and utility costs. A retail business might demonstrate stock turnover and repeat demand. The bank needs a plausible repayment story supported by records—not only an optimistic sales projection.
Estimate instalments under three outcomes
Build a base case, a slower-sales case and a delayed-launch case. The listed terms permit up to five years and describe limited grace periods for some businesses, but grace is not a waiver of eventual principal repayment. Set monthly cash aside from operating profit after rent, salaries, taxes and stock replenishment. For collateral, account for the possible consequences if the Asaan Karobar Finance does not perform. Get the signed conditions and fee schedule before creating binding obligations.
Practical dividing line: Small vendors considering a limit up to Rs 1 million may wish to compare the Card product separately. The Finance programme’s NTN, tax-filer and premises requirements deserve their own eligibility check.
How Asaan Karobar Finance works in practice
For a entrepreneur, the practical question is not only whether Asaan Karobar Finance exists. It is whether the published programme addresses the actual need involving business, who reviews the finance application, and how the applicant will receive a formal response. The institutional role is important because an intermediary website cannot change an outcome.
Tier 1 comprises PKR 1 million to PKR 5 million and a PKR 5,000 processing fee with a personal-guarantee structure. This affects how somebody should prepare and whom they should ask for a decision. If the applicant cannot establish this condition, the sensible step is to contact Government of Punjab before investing in paperwork, travel or third-party services.
Tier 2 comprises PKR 6 million to PKR 30 million, with a PKR 10,000 processing fee and secured-financing requirements. Do not extend that sentence beyond what it says. Published policy language can describe a limit, a coverage rule or an eligibility test rather than a promise that every applicant receives the same service. Ask for a current written explanation where the original webpage is ambiguous.
Treat the finance application as one stage of a process. Initial registration, identity confirmation, document review, credit and viability checks and a final written decision may be separate. Saving dates and official reference numbers makes the process easier to follow without relying on messages from unknown agents.
An applicant researching Asaan Karobar Finance should preserve the official reference alongside any supporting record.
Eligibility for Asaan Karobar Finance: who should check first
Eligibility begins with the official definitions, not with a social-media headline. For Asaan Karobar Finance, review the authority, geography, relevant records and product category. The listed customer markup rate is 0%, with a maximum tenure of five years. This particular detail can change which applicant profile or situation the scheme is intended to serve.
If the applicant is unsure whether they fall within the published scope, first contact programme lender. Ask which evidence is acceptable and whether the presently announced phase covers their situation. This is especially helpful for people with joint ownership, informal income, family businesses, inherited land or older identity information.
- Punjab’s Asaan Karobar Finance programme supports qualifying small and medium enterprises.
- The listed customer markup rate is 0%, with a maximum tenure of five years.
- The published eligibility includes age 25–55, Punjab residence and business location, active FBR filer status and a clean credit history.
- Tier 1 has a PKR 5,000 published processing fee; Tier 2 has PKR 10,000.
The next step with Asaan Karobar Finance is to confirm the specific notice or phase that applies to the reader’s situation.
Limits, fees and the practical budget
For Asaan Karobar Finance, separate published headline benefits from costs borne by the user. The published eligibility includes age 25–55, Punjab residence and business location, active FBR filer status and a clean credit history. The amount or concession must be read together with its intended purpose, permitted spending, payment route and any associated documents. An applicant should not interpret an illustrative maximum as an individual entitlement.
Published handling charges differ by new/existing business; legal, valuation and insurance expenses may apply. Where exact charges, fees or interest terms are not in the official information cited here, no assumed amount is supplied in this guide. The right number is the amount stated by the responsible office or lender for the specific product and date.
The Asaan Karobar Finance says 0% customer markup but other costs, including legal and handling charges, may arise. In practice, a short written budget can help: list the fee, security or contribution, one-time registration costs, any recurring payment and a small emergency margin. If this is a service or scholarship rather than a loan, the same principle applies to travel, document preparation and other legitimate incidental expenses.
Under Asaan Karobar Finance, the authority’s written terms should take priority over third-party assumptions.
Documents for Asaan Karobar Finance
The records most relevant to this application are business and identity records. Start with your valid identity details and the evidence that connects you to the programme: for example, verified enrollment for a scholarship, source transactions for a complaint, bankable business activity for an SME loan or land and stock records for farm support. These are examples of document types, not a fabricated fixed list.
If a programme publishes an official checklist, use that checklist over generic online advice. Punjab describes limited grace periods and equal monthly instalments under the actual sanction terms. The same identifying data should appear consistently across all related records; mismatched spellings, outdated mobile numbers and unclear ownership evidence can cause delay.
A business forecast should explain customers, operating expenses, expected revenue and debt service, not just a proposed purchase. Keep clean copies in a folder with clear filenames, retain original documents where required and never hand over passwords, one-time verification codes or identity scans to an unverified person.
Practical document rule: The official programme or lender sets the definitive checklist. Never upload sensitive documents to an unofficial imitation portal.When comparing Asaan Karobar Finance, it is useful to separate the published framework from each institution’s final decision.
How to use Asaan Karobar Finance through official channels
Begin with Government of Punjab and the official source linked below, rather than searching for a paid agent. Read the current notice, determine whether there is a live application period or complaint channel, and check that the website address is genuine. A legitimate official link is more useful than a viral advertisement promising instant results.
Then identify the correct finance application. Enter accurate information and review each field before submitting. Save the receipt, acknowledgment, reference number, or confirmation email according to the portal’s instructions. An error in a CNIC or telephone number can make later follow-up much harder.
Marketing phrases such as interest-free describe one price component; applicants must also examine fees, taxes, instalments and guarantees. A message that says “submitted” is not necessarily a positive decision. Wait for the institution’s next formal step and only provide additional records using a verified channel. Fees, if any, should be paid only through a mechanism officially displayed by the provider.
T2 is secured financing and can require valuation and collateral paperwork. If a form is temporarily unavailable, do not improvise an unofficial alternative. Check the Asaan Karobar Finance notice and service contact details, then return when the authority confirms that its window is open.
- Verify the announcement — Read the live official page for this particular scheme or service.
- Check your eligibility — Compare the published scope with your own records and intended purpose.
- Organize your information — Prepare only the documents requested by the real authority.
- Submit safely — Use the approved application or complaint route and review before sending.
- Keep the evidence — Save an acknowledgement and any relevant receipt or reference number.
- Follow up — Respond to official enquiries and avoid people claiming to guarantee results.
A careful review of Asaan Karobar Finance means checking the cited facts before giving another person confidential information.
Common application situations and how to respond
①Situation 1A new small factory owner requests Tier 1 and budgets the application fee and investment contribution.
②Situation 2A company needing expansion funding above PKR 5 million considers Tier 2 security and valuation costs.
③Situation 3An established Punjab retailer compares the 3% annual handling charge with a startup’s published fee position.
④Situation 4A sole proprietor wants to understand why a tax filer record and viable business premises matter for eligibility.
Situation 1: A new small factory owner requests Tier 1 and budgets the application fee and investment contribution. The sensible action is to check the applicable published rule, gather the directly relevant records, and write down the question for Government of Punjab or the responsible institution. When comparing possible options, consider actual costs, eligibility, timing and obligations rather than relying on a best-case approval scenario.
Situation 2: A company needing expansion funding above PKR 5 million considers Tier 2 security and valuation costs. The sensible action is to check the applicable published rule, gather the directly relevant records, and write down the question for Government of Punjab or the responsible institution. When comparing possible options, consider actual costs, eligibility, timing and obligations rather than relying on a best-case approval scenario.
Situation 3: An established Punjab retailer compares the 3% annual handling charge with a startup’s published fee position. The sensible action is to check the applicable published rule, gather the directly relevant records, and write down the question for Government of Punjab or the responsible institution. When comparing possible options, consider actual costs, eligibility, timing and obligations rather than relying on a best-case approval scenario.
Situation 4: A sole proprietor wants to understand why a tax filer record and viable business premises matter for eligibility. The sensible action is to check the applicable published rule, gather the directly relevant records, and write down the question for Government of Punjab or the responsible institution. When comparing possible options, consider actual costs, eligibility, timing and obligations rather than relying on a best-case approval scenario.
Anyone using Asaan Karobar Finance should confirm whether the official portal is currently taking submissions.
Mistakes that cost applicants time or money
The first mistake is assuming that every claim made online about Asaan Karobar Finance applies to every applicant. A current scheme page may coexist with an older announcement, and a different financial product may have a deceptively similar name. Always inspect the date, issuing authority and eligibility scope.
An active FBR filer record and Punjab business residence are published eligibility components. This detail deserves attention because people may arrange finances or documentation around it. If the rule is unclear, ask a focused question rather than accepting a confident but unsupported answer from an unverified website.
Another common mistake is forgetting the nonfinancial conditions: use of approved suppliers, the exact applicant classification, a required registration, a documentation standard, or a restricted appeal route. Those requirements can matter as much as the advertised amount or benefit.
Finally, avoid overstating what a form submission proves. Keep your own documentation, seek written responses and do not assume that a successful upload, SMS confirmation or balloting entry means the final obligation or benefit has been approved.
- Tier 1 has a PKR 5,000 published processing fee; Tier 2 has PKR 10,000.
- The programme says 0% customer markup but other costs, including legal and handling charges, may arise.
- T2 is secured financing and can require valuation and collateral paperwork.
- An active FBR filer record and Punjab business residence are published eligibility components.
The practical value of Asaan Karobar Finance depends on whether its conditions match the applicant’s real circumstances.
Choose the correct Asaan Karobar Finance tier
The key distinction is not simply how much money you would like. Tier selection affects security, proof of repayment capacity, documentation work and the potential loss if the business performs badly.
Tier 1: eligible smaller enterprises
- Rs 1–5 million is the published Tier 1 range. Ask whether the requested amount fits a realistic purpose and whether personal guarantees cover the bank’s security requirement.
- Show predictable operating receipts. Existing sales, customer contracts, tax filings and a careful cost estimate can make the repayment story clearer.
- Distinguish a guarantee from a gift. Interest-free pricing does not remove the legal obligation to repay the facility.
- Check the processing expense. Punjab guidance lists Rs 5,000 for Tier 1; make the payment only through an authorised channel.
Tier 2: larger secured financing
- More than Rs 5 million up to Rs 30 million is the published range. Security and formal financial assessment become central rather than optional paperwork.
- Understand collateral risks. A business owner should know which asset is charged, what valuation costs apply and what happens after default.
- Prepare investment evidence. Machinery quotes, construction estimates or other eligible capital expenditure should be defensible and linked to the operating plan.
- Check the Rs 10,000 published processing charge. Ask the lender to identify any additional legal, valuation or documentation costs.
Make the numbers support the application
Build a forecast a bank can examine
- Separate sales from profit. A shop with high revenue can still be unable to repay if stock costs and wages absorb most of the cash.
- Use conservative assumptions. Explain why demand should exist and show a lower-sales scenario, particularly for new ventures.
- Match repayment to the business cycle. A seasonal mill, agricultural supplier or service contract cannot always fund equal monthly instalments from day one.
- Account for the stated grace period. Public information describes up to six months for new businesses and up to three for existing firms; ask how interest-free principal repayment begins in your actual offer.
Show how the finance will be used
- Working capital: Explain stock purchase, receivables or operating needs with invoices and timelines.
- Expansion: Connect new equipment or premises to measurable additional capacity rather than vague claims of ‘growth’.
- Recordkeeping: Prepare NTN, active filer proof and accurate business registration details before the bank requests them.
- Cash contribution: If the lender requires owner equity or security, identify the source clearly; do not assume 0% markup means no owner contribution.
Prevent delays and avoid expensive misunderstandings
Before submission
- Check the 25–55 age condition. A technically excellent proposal will not override a published applicant-age limit.
- Review filer and credit status. Missing NTN, inactive tax status or undisclosed obligations can trigger preventable queries.
- Prepare a lender-ready folder. Keep identity, ownership, accounts, tax record, purpose documents and collateral material in a consistent order.
Before accepting an offer
- Compare signed amount with requested amount. If the bank approves less, update the investment plan rather than leaving an unfunded gap.
- Ask about security release. Understand when pledged documents or assets are released after final repayment.
- Read default and early-settlement clauses. These determine actual obligations regardless of marketing language about ‘interest-free’ business finance.
A finance-tier decision exercise
Choose the smallest viable facility that funds the approved investment. This avoids unnecessary collateral exposure and makes the repayment plan easier to explain.
A business seeking equipment
- Identify the productive asset. Specify machine, quoted price and expected improvement in output or quality.
- Estimate realistic extra orders. New capacity has no value if demand is not demonstrated.
- Calculate maintenance and staffing. Equipment can increase operating expense as well as sales.
- Check whether Tier 1 is sufficient. Borrowing above the threshold merely to access more cash can introduce collateral requirements.
A business seeking a larger expansion
- Explain why Tier 2 is necessary. The investment should be linked to capacity, working capital and achievable revenue.
- Map collateral obligations. Owners need to know exactly what asset may be at risk on default.
- Show owner equity and past accounts. An interest-free rate does not eliminate underwriting or credit assessment.
- Test a lower-sales scenario. If repayments rely on perfect demand, the expansion plan may be too aggressive.
Before final acceptance
- Compare the approved amount with the cost plan. An underfunded project can stall and still leave debt outstanding.
- Read all charges. Processing, valuation and documentation can differ from the advertised markup rate.
- Check the grace period and first instalment. Verify whether the business will generate cash before principal repayment starts.
- Keep a signed schedule and copies. These are more authoritative than an unofficial online eligibility calculator.
Final checks before submitting or spending money
- Build a short written budget for the specific scholarship, home, farm, business or employment costs discussed in this guide; do not rely on an advertised maximum.
Three applicant situations: what to do next
These are realistic planning examples, not reports of verified applicants or promises of acceptance.
Startup considering Tier 1 finance
Build credible equipment quotations, cash-flow projections and NTN documentation before applying. A personal guarantee is a serious repayment obligation.
Established SME seeking new machinery
Tier 2 may involve secured finance and valuations; the business should compare asset productivity with the repayment schedule under low and high sales scenarios.
Business operating informally without tax records
Do not invent an NTN or filer record. Address registration and the correct premises documentation before applying for this product.
Official sources and editorial disclosure
Research checked against the public government, HEC, banking or PSDF material linked here on 12 November 2026. Conditions, allocations, registration windows and pricing can change. Confirm the latest publication with the actual issuing authority before applying. Scheme Info is an independent information publisher; it is not a lender, scholarship administrator, application representative or government department.
Frequently asked questions
Is Asaan Karobar Finance the same as the Card?
No. The finance product supports larger SME lending, separate tiers and additional eligibility requirements.
What is Tier 1?
Published Tier 1 covers Rs 1–5 million with personal guarantees.
What is Tier 2?
The secured higher tier offers financing up to Rs 30 million, subject to bank assessment.
Is the borrower interest rate zero?
The public scheme describes 0% end-user rates, but fees and other liabilities may still apply.
Must I have an NTN?
Yes, official eligibility requires a valid NTN and relevant tax registration/filer status.
What is the age limit?
The published age band is 25–55 years.
What are the fees?
Public details list Rs 5,000 Tier 1 and Rs 10,000 Tier 2 processing fees.
How long can repayment take?
Published terms mention up to five years, with potential limited grace depending on business category.
Can a prospective startup apply?
Public guidance includes new ventures, but the applicant must meet business feasibility, NTN, tax and bank checks.
What must a Tier 2 borrower consider?
Secured financing can require collateral, valuation and a clear repayment plan; the 0% headline does not remove those obligations.