Loan Scheme In Pakistan: Compare Federal, Punjab And Specialist Programmes
The phrase loan scheme covers several unrelated programmes. Compare the purpose, eligible age and location, financing limit, subsidy rate and application channel before making a commitment.
The Short Answer
Federal youth business finance, Punjab Asaan Karobar products and subsidised housing programmes have separate rules. On 10 November 2026 the federal government announced a new Tier 4 for the PM Youth Business and Agriculture Loan Scheme up to Rs 25 million at 8%; older bank pages may still describe only three tiers.
Federal And Provincial Finance Options
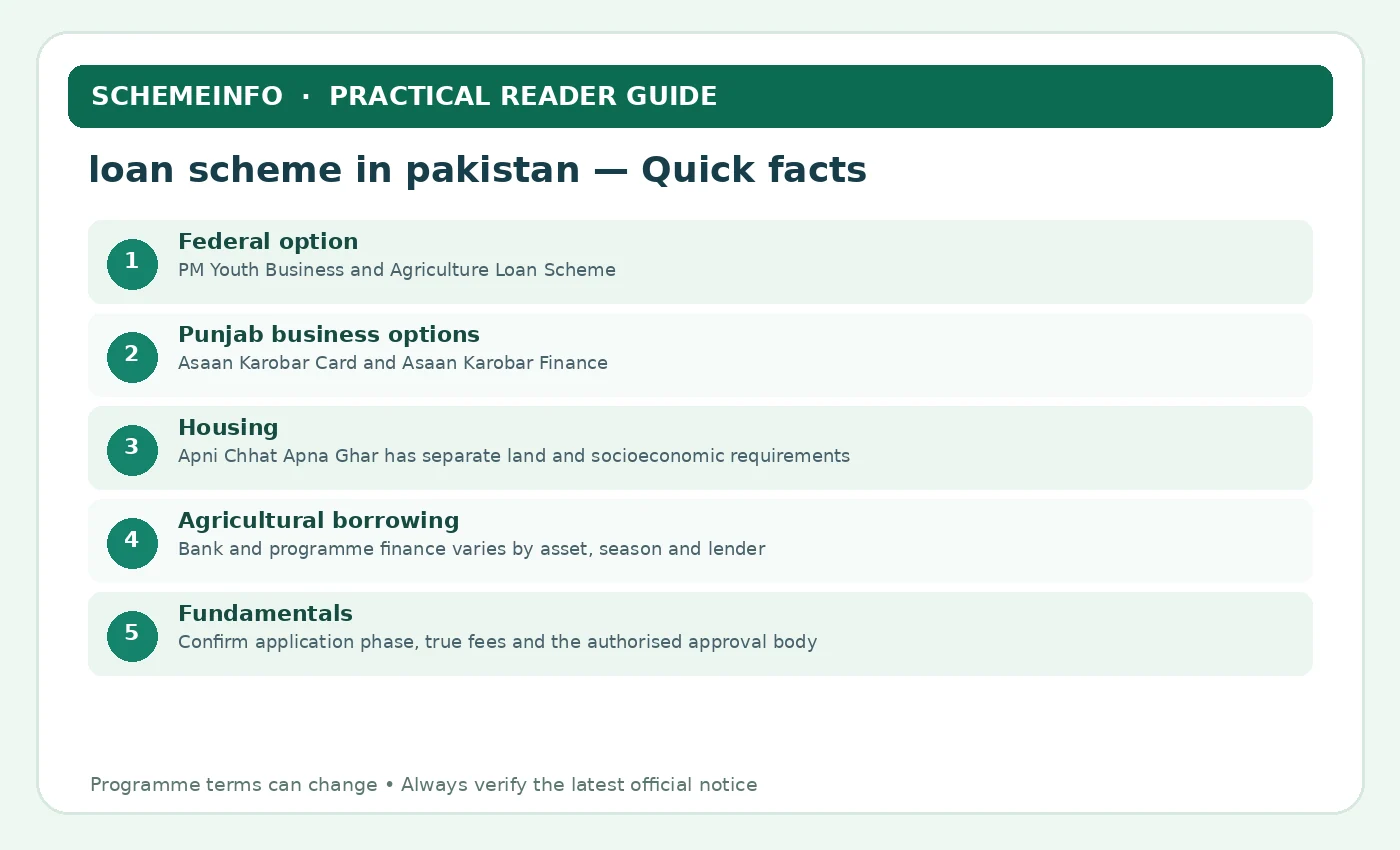
These are the central published facts for this programme, not a guarantee of admission, approval or an open registration window. The references at the bottom distinguish current official pages from historical phases.
| Federal option | PM Youth Business and Agriculture Loan Scheme |
|---|---|
| Punjab business options | Asaan Karobar Card and Asaan Karobar Finance |
| Housing | Apni Chhat Apna Ghar has separate land and socioeconomic requirements |
| Agricultural borrowing | Bank and programme finance varies by asset, season and lender |
| Fundamentals | Confirm application phase, true fees and the authorised approval body |
Lender Eligibility And Borrower Suitability
Begin with the responsible institution’s written eligibility rules for this loan option. These checks are not a promise of approval; eligibility is decided through the named programme’s actual verification process.
- Valid identity and residency evidence matching the selected programme, usually CNIC and relevant provincial residence requirements.
- Age and employment or business status within the provider’s published range; PM Youth generally lists 21–45, with an IT/e-commerce exception at 18.
- A genuine financing purpose matching the programme: business, agriculture, housing or another specifically allowed activity.
- Ability to meet the required monthly payments, security, tax registration and credit checks where applicable.
- Any geographic, family-income, property-ownership or prior-benefit restrictions published for that particular scheme.
- Submission through the relevant official portal, bank or authorised branch; there is no single all-scheme registration form.
Documents For Loan Scheme In Pakistan: Records And Proof
Keep essential records legible and separate from optional supporting papers. For this loan option, confirm which forms the responsible office requires before sharing identity or family information.
- CNIC and applicant-controlled mobile number.
- Proof of address or domicile if a scheme restricts eligibility by province or district.
- Business registration, NTN, tax filing and premises evidence for applicable SME products.
- Business plan, quotations, crop/land records, vehicle documents or construction estimates where those purposes are financed.
- Income, bank statements, guarantor/security and existing-liability declarations where the lender asks.
- Keep any official acknowledgement, reference number, sanctioned offer and repayment schedule.
How Programme Eligibility And Underwriting Differ
Use these programme-specific details to check the official route and to avoid interpreting a rule more broadly than it was written.
Identify The Purpose Before Choosing A Programme
Federal and provincial schemes are not interchangeable. A crop-input need, a rented-shop expansion and construction on a family-owned plot have different financing risks and evidence. write down the purchase or expense first, then match that exact purpose against each provider’s list of permitted uses. Resist choosing only by the largest advertised amount. For applicants, write down the rule in your own words and identify which document could demonstrate it. This turns a broad claim into a checkable requirement rather than a hopeful assumption. An applicant whose CNIC address is old may need to correct identity or residence records before the main application is even considered. A bakery needing an oven could explore SME financing, whereas a household seeking to build on a small owned plot should begin with housing criteria rather than a commercial card.
PM Youth Business And Agriculture Financing
The federal PM Youth Business and Agriculture Loan Scheme uses participating banks and an online-only application. The official portal still outlines earlier tiers up to Rs 7.5 million; the federal announcement of 10 November 2026 adds a fourth tier up to Rs 25 million. Confirm the new tier with the participating bank. Check whether your age, intended enterprise and projected repayment fit the current tier. Compare business and agriculture options under the same federal umbrella before filling in the bank form. For readers researching this loan option, keep the sequence of actions straight: registration, eligibility screening, document validation, final approval and payment are often different stages. Completing the first does not establish completion of the last. A confirmation SMS may only prove the form reached a system. It is not the same as a signed offer, disbursement schedule or selected-ballot status.
Punjab Asaan Karobar Finance Compared With Card
Punjab’s Finance programme addresses larger SMEs and uses tiers that differ from the digital Asaan Karobar Card, which targets smaller businesses with structured spending. Both use 0% borrower markup but publish other charges. compare the official fee schedule, tax requirements, security and business premises rules instead of assuming that “interest-free” means no paperwork or cost. For applicants, the cost of a financing facility should be evaluated across its full life, including processing, insurance, registration, penalties and time away from work—not from a headline zero-markup rate alone. A qualifying established manufacturer seeking several million rupees should not submit the same evidence as a new corner-shop operator seeking card-based working capital.
Housing Support Is A Separate Decision
Punjab’s Apni Chhat Apna Ghar programme supports construction for eligible residents already owning small qualifying plots, while the free-plot Apni Zameen Apna Ghar initiative serves another housing need. determine whether the person has land, needs land or wants to purchase a finished property. Each outcome has a different official route and should never be promised interchangeably. For applicants, this is an area where old screenshots can be misleading. A family without a registered plot should not be told to apply for a construction loan that explicitly requires ownership evidence.
Compare The Federal Loan Tiers Published In November 2026
The Prime Minister’s Youth Business and Agriculture Loan Scheme was expanded in a 10 November 2026 federal announcement. Its published tiers are: up to Rs 500,000 at 0%, above Rs 500,000 to Rs 1.5 million at 5%, above Rs 1.5 million to Rs 7.5 million at 7%, and a newly announced Tier 4 above Rs 7.5 million to Rs 25 million at 8%. Tier 4 is intended for scaling qualifying enterprises, not as an instant personal spending loan.
Check the live official form for implementation of Tier 4 before choosing an amount. Some participating banks still publish an older three-tier product page. This inconsistency should trigger a request for current written terms, not a guess that the bank will automatically process the new tier.
A business borrower should also plan equity, security, cash flow and the intended spending categories. Matching a subsidy ceiling does not mean the lender is obliged to advance the maximum.
- Confirm the latest tier with the participating lender
- Match the amount to business sales and forecasts
- Do not confuse an announced policy ceiling with personal approval
Programme Purpose, Approval And Funding
Akhuwat And Community Microfinance
Akhuwat’s Islamic Microfinance operates a branch-based Qarz-e-Hasan model, rather than the government’s bank-led business tiers. Its official website says applications are made through branches, not online agents. identify the nearest authentic branch and ask for the current product, guarantor and assessment instructions. Never pay someone who claims to sell an automatic online Akhuwat approval. For applicants, applicants should use their own registered contact details and keep the submission number private. A low-income trader may value a smaller local assessment route more than a larger bank product requiring formal tax and business records.
Agriculture Financing Is Not Always A Subsidy
ZTBL and other agricultural lenders offer products with different crop, tractor, livestock and storage purposes. A normal tractor loan does not become the provincial Green Tractor subsidy just because both support farm equipment. Compare machinery ownership, collateral, repayment dates linked to harvests and the actual source of any claimed government contribution. For readers researching this loan option, it helps to separate a scheme’s rules from a lender’s underwriting. A dairy operator might need animal or feed finance, whereas someone acquiring a tractor should evaluate financing and subsidy programme conditions separately.
Bank Charges And The Meaning Of Zero Markup
A government may subsidise the interest portion but a programme can still charge processing, legal, insurance or late fees. Punjab’s official SME programme pages list specific processing charges and other terms. ask the issuing bank for a written amount-to-be-received, total-to-be-repaid and fee schedule before signing. Do not calculate affordability from nominal markup alone. For applicants, a practical reader can make a document folder with three groups: required at submission, conditional after verification and optional material for a later appeal. A financing offer of Rs 1 million with a charge deducted from disbursement needs a different cash-flow plan from an offer where all approved funds are paid intact.
Age, Residence And Identity Checks
The PM Youth portal has a different age range from the Punjab Asaan Karobar Finance and Card schemes. Many provincial programmes also require the enterprise and applicant to be located in that province. Check the wording for age at application, residence on CNIC and business address. A national ID alone does not make every citizen eligible for every provincial incentive. For readers researching this loan option, the best question to ask before applying is what happens if the answer is no. A 22-year-old entrepreneur may fit the federal age requirement and the Punjab Card but not the main Punjab Asaan Karobar Finance age threshold.
Choosing The Right Borrowing Route
Beyond the headline amount, these details help a borrower compare the offer, prepare reliable evidence and avoid avoidable costs. Financial terms and availability always depend on the actual lender or programme.
Choose By Purpose Before Browsing Amounts
A government-branded figure is not automatically the right facility for your needs. Product purpose is often an eligibility condition, not an optional preference.
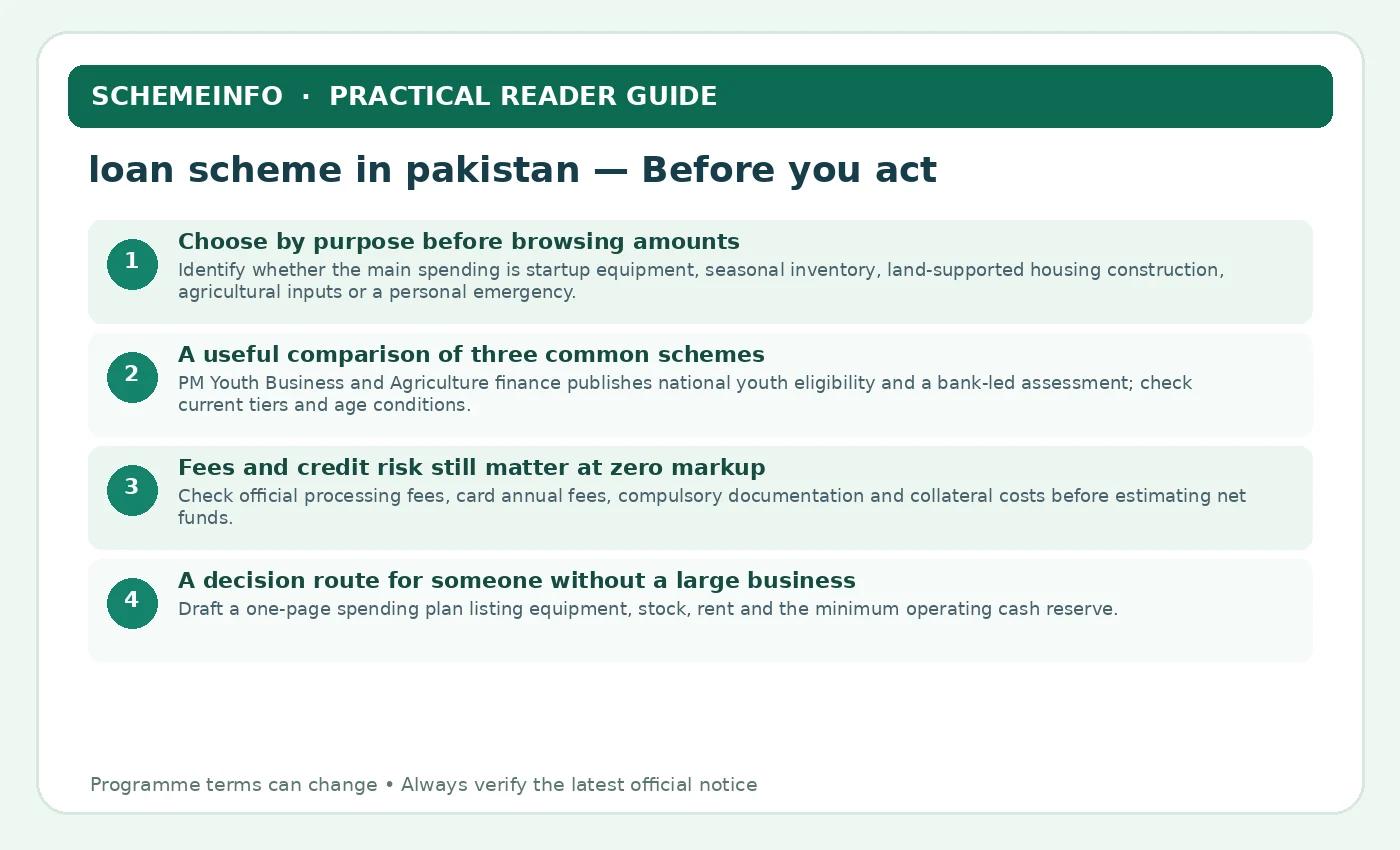
- Identify whether the main spending is startup equipment, seasonal inventory, land-supported housing construction, agricultural inputs or a personal emergency.
- Check the target province and whether the applicant’s residence and business premises meet each scheme’s geographic criteria.
- Find the implementing bank or department and whether applications go through a portal, a branch or a selected partner.
- Confirm if funds are cash, restricted digital spending, vendor payment, asset financing or a reimbursement-style benefit.
- Only after those checks compare limits; the highest advertised ceiling is not the amount an individual applicant will receive.
The fastest way to waste an application is to begin with a scheme whose permitted purpose does not match the expense.
A Useful Comparison Of Three Common Schemes
Consider a federal business programme, a provincial SME card and a more substantial Punjab finance facility. Their designs answer different financing needs.
- PM Youth Business and Agriculture finance publishes national youth eligibility and a bank-led assessment; check current tiers and age conditions.
- Punjab Asaan Karobar Card targets smaller enterprises, uses restricted business transactions and has specific card-related charges.
- Punjab Asaan Karobar Finance targets larger SME needs with separate tiers, tax requirements and potentially security.
- Housing construction assistance should be checked against landownership and household criteria; it is not a general shop loan.
- Charitable microfinance may involve branch-level community assessment and a much smaller facility than major SME products.
Put annual sales, project budget, net income and proof of business activity on the comparison worksheet before choosing.
Practical Risk And Application Checks
Beyond the headline amount, these details help a borrower compare the offer, prepare reliable evidence and avoid avoidable costs. Financial terms and availability always depend on the actual lender or programme.
Fees And Credit Risk Still Matter At Zero Markup
Policy-backed financing can have low or zero end-user markup but still carry important fees and conditions. Repayment has a cost even without interest.
- Check official processing fees, card annual fees, compulsory documentation and collateral costs before estimating net funds.
- Ask whether an upfront contribution is required for vehicles, machinery or secured business projects.
- Compare the instalment against the business’s weakest ordinary month, not a projected first-quarter growth target.
- Understand that a government programme may still require credit history checks and can reject an otherwise plausible applicant.
- Keep personal and business expenses separate because programme funds may be restricted to specific purposes.
A rate of 0% is useful only when the complete financial obligation is affordable and understood.
A Decision Route For Someone Without A Large Business
Many searches are made by people starting with a small idea, modest savings and incomplete documentation. They can prepare useful evidence before applying.
- Draft a one-page spending plan listing equipment, stock, rent and the minimum operating cash reserve.
- Take simple records of current sales, orders or farm output rather than inventing large forecasts to meet a programme ceiling.
- Check whether a tax registration or business premises proof is mandatory for the specific product; do not assume every scheme requires the same.
- If the facility is not presently accepting applicants, retain the evidence and monitor the named official portal rather than paying an agent.
- Consider a smaller pilot or gradual purchase when financing is uncertain or proposed instalments absorb most of the expected cash surplus.
A credible, right-sized proposal is more valuable than ten copied application forms.
Borrower Decision Worksheet: Loan Scheme In Pakistan
Work through these questions before providing personal records or accepting a financing offer. This is an independent decision tool, not a lender application form. Write the evidence or published rule that answers each question.
- Decision 1: Which named lender, department or licensed company would make the actual decision?
- Decision 2: Is this the currently authorised application route, and what date is the guidance from?
- Decision 3: What amount would reach my account after processing and other authorised deductions?
- Decision 4: What exact dates and amounts would I repay, including any compulsory fees?
- Decision 5: How much remains after rent, food, utilities, transport and all existing repayments?
- Decision 6: What happens to collateral, guarantors or credit records if I miss a payment?
- Decision 7: Can I prove the spending purpose and funds use with appropriate business or personal records?
- Decision 8: Where is the responsible organisation’s official complaints and correction channel?
Four Checks Specific To This Financing Question
Only after those checks compare limits; the highest advertised ceiling is not the amount an individual applicant will receive.
Charitable microfinance may involve branch-level community assessment and a much smaller facility than major SME products.
Keep personal and business expenses separate because programme funds may be restricted to specific purposes.
Consider a smaller pilot or gradual purchase when financing is uncertain or proposed instalments absorb most of the expected cash surplus.
The purpose of a worksheet is to prevent one misleading number from deciding the entire choice. Compare the original source, the actual offer and the household budget. If any one of these is missing, the sensible next action is further verification rather than signing.
Distinguish Punjab Card Finance From SME Finance
Punjab’s Asaan Karobar Card is a digital small-business financing product with structured usage and a published ceiling of Rs 1 million. The larger Asaan Karobar Finance scheme instead covers eligible SMEs with two financing tiers and different documentation, business premises and security requirements.
The relevant PSIC page lists Finance Tier 1 from Rs 1 million to Rs 5 million and Tier 2 above Rs 5 million to Rs 30 million, with published processing fees of Rs 5,000 and Rs 10,000 respectively. It also sets a 25–55-year age range and credit-history and NTN conditions. Those requirements cannot simply be applied to every other Punjab loan product.
A home-based trader needing stock purchases may prefer a smaller product that permits the intended digital spending; a registered manufacturer acquiring machinery may need the larger finance route. Neither product is a grant.
- Check whether the intended purchase can be financed
- Compare fees, guarantees, collateral and contribution rules
- Read the official programme page before opening a form
Worked Programme Fit: Same Applicant, Three Different Financial Needs
A Punjab small-business owner might also want to repair a home and buy machinery. Three objectives should not be placed into one application simply because several public programmes advertise large financing amounts.
| Rs 250,000 inventory need | Potential small-enterprise product; verify approved business use |
|---|---|
| Rs 4 million factory expansion | Potential larger SME finance; tax and security rules relevant |
| House construction on owned land | Housing programme with plot and household criteria |
| Agricultural input purchase | Crop or agriculture-specific facility |
| Essential question | Which programme legally permits this expense? |
What The Comparison Means Before You Act
- Asaan Karobar Card’s published ceiling is up to Rs 1 million, but a smaller business may qualify for less and must use funds appropriately.
- Asaan Karobar Finance covers larger business purposes with separate tiers and documentary conditions.
- Apni Chhat Apna Ghar assesses qualifying property and family circumstances; it is not unrestricted capital for any project.
- For a federal youth loan, compare its own age, amount and bank assessment rules, not those from a provincial card.
- If a programme is temporarily closed, do not pay a broker to force entry or claim that another scheme’s form is interchangeable.
- Separate every purpose, budget, permitted use and repayment source before choosing the official application channel.
Matching the use of money to the named scheme prevents both wasted applications and later misuse of restricted funds.
Illustrative worksheet: Figures are educational examples, not a real lender quotation or confirmed approval. Always use the responsible institution’s current written terms.
Two Realistic Loan Scheme In Pakistan Situations
These scenarios are illustrations, not real applicants, case-law findings or promised outcomes. Their purpose is to show what a careful next decision looks like when one key detail is uncertain.
A Shop Owner Applies To A Housing Programme
The applicant needs stock, not home construction. A Punjab business product or another appropriate lender is the sensible area to check; the housing route restricts how money may be used.
A Young Farmer Has No Steady Salary
A seasonal farm business may need crop-linked repayment and evidence of input costs. The applicant should compare agriculture finance rather than copy a salaried personal-loan budget.
Choose Your Next Official Application Step
Loan applications differ by lender and programme. Follow the authorised current procedure, and separate application submission from credit approval and money being deposited.
- Name the exact product: Identify the licensed bank, NBFC or department responsible for loan scheme in pakistan. Confirm its official portal or branch before providing information.
- Check whether it suits the purpose: Match the product’s geographic, age, income, security, tax and business-purpose rules to your situation, without assuming every lender has the same criteria.
- Calculate the real budget: Write down the expense that needs funding, money you can contribute, net cash required and the instalment that remains affordable in a weak month.
- Prepare truthful records: Make required identity, income, employment or business records consistent; do not pay an agent to alter credit or eligibility data.
- Apply through the proper channel: Use the verified online system or branch, save the acknowledgement and never share an OTP or PIN with a supposed loan officer.
- Read the offer before agreeing: Check the written amount, fees, net proceeds, repayment schedule, security, consent, default and complaints terms before signing or accepting digitally.
- Keep records after funding: Save the agreement, disbursement receipt, instalment record and lender contacts. If there is a problem, use the institution’s documented complaint process.
Official Loan Scheme In Pakistan Sources And Independence
The links below are owned by the programme administrators or responsible public bodies. Their current instructions outrank summaries and old dates. SchemeInfo is an independent information publisher: it is not a government agency, bank, lending institution or government loan administrator.
Editorial review: 12 November 2026. Scheme rules and payments may change after this date. Verify before applying or sharing sensitive personal information.
Create A Scheme Comparison With Three Real Needs
Imagine three borrowers: a 24-year-old online seller seeking Rs 300,000, a 39-year-old Punjab workshop owner planning Rs 4 million in machinery and a first-time buyer financing a residential property. Their financing needs differ, so a useful comparison must show which programme is designed for each purpose.
The young seller might explore the PM Youth scheme or a qualifying smaller Punjab card, subject to age and trading rules. The workshop should review the separate Punjab SME Finance underwriting, NTN and premises criteria. The housing buyer should investigate the renamed federal subsidised home finance programme and lender property checks.
Do not use a single “register now” link for all three. Save programme names, current application links, written product terms and applicant reference numbers separately.
- List the exact provider and governing programme
- Check whether the borrower qualifies by age and region
- Keep scheme-specific papers in distinct folders
Official Sources And How To Verify Updates
Official programme notices and lender instructions take precedence over older articles, screenshots and social-media posts. Check the precise phase, date and applicant category before submitting personal details.
Related SchemesInfo Reading
For related topics, explore the following site searches. Each subject has its own rules and application procedure, so do not transfer eligibility requirements between programmes.