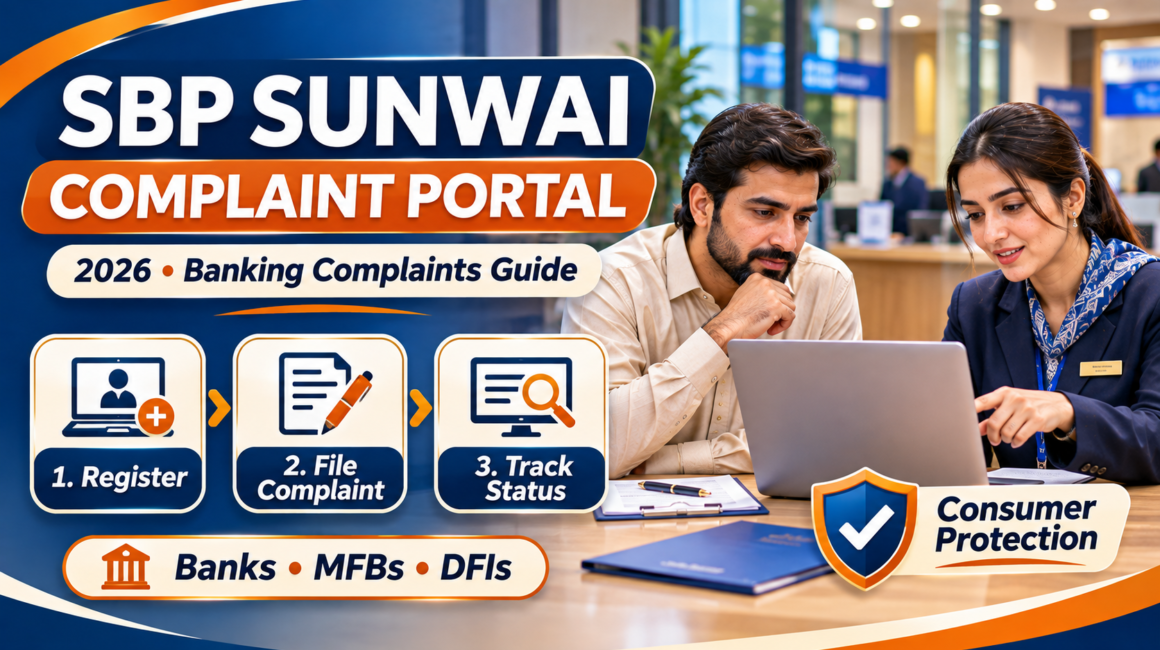
A banking complaint needs evidence, the correct forum and a clear paper trail. This guide explains how SBP Sunwai helps customers file, track and escalate complaints safely.
Table of Contents
The SBP Sunwai Complaint Portal is an official channel for banking customers to submit and monitor grievances. It connects the complaint to the appropriate institution or oversight forum; it does not approve loans, cancel a debt or guarantee that a disputed charge will be refunded.

Eligibility criteria: who should check first
The points below distinguish official programme conditions from practical preparation. Meeting a checklist is not a guarantee of bank, regulator or programme approval.
- You are an identifiable banking-service customer or a person with a genuine, documented banking grievance.
- The concern involves a bank, microfinance bank, development finance institution or a banking matter covered by the applicable complaints process.
- You can provide contact details and a factual description of what happened.
- You can identify the institution, relevant account or service without publishing secret credentials.
- You understand that some disputes are outside SBP or Banking Mohtasib jurisdiction and may be redirected.
When checking SBP Sunwai Complaint Portal, distinguish published criteria from a banker’s, agent’s or social-media interpretation; the issuing institution makes the final decision.
Required documents and supporting records
Prepare documents in a separate folder before opening an application or official complaint page. Some items are conditional; do not submit a document unless the real institution requests it.
- Valid CNIC details and current phone/email for registration or identification, when requested through the official portal.
- Bank or branch name and location, relevant service/product and approximate transaction date.
- Earlier complaint reference number, date, and copies of the bank’s response or acknowledgement.
- Relevant transaction statement extract, receipt, bank letter or screenshots with sensitive data redacted as appropriate.
- A dated timeline and a short statement of the correction or action you seek.
- Copies rather than original identity documents or original bank records when sharing supporting evidence.
For SBP Sunwai Complaint Portal, prepare only the records relevant to your own situation, and keep original identity or ownership papers in your possession unless a verified institution lawfully requires them.
The official rules at a glance
| Topic | What the published guidance says |
|---|---|
| Service type | Banking complaint filing and tracking |
| Who operates it | State Bank of Pakistan |
| Who receives complaints | Banks, MFBs, DFIs; relevant statutory forum depending on case |
| First step | Contact the concerned financial institution and document the response |
| Escalation | Banking Mohtasib generally after 45 days without a satisfactory response, subject to case type |
| Official website | sunwai.sbp.org.pk |
These points summarise published conditions. They do not replace the full official notice, a financial contract or a current application-window announcement.
Use the summary of SBP Sunwai Complaint Portal as a reading aid, not a substitute for the latest official circular or complete terms.
What readers should confirm in 2026
What an acknowledgement proves—and what it does not
An acknowledgement from the complaints portal confirms receipt of the information entered. It should not be treated as a finding that the bank is at fault. Preserve the reference number together with the version of the complaint you submitted, because a bank may ask for a transaction number, statement, correspondence or proof that you first contacted its complaints team.
For account fraud, do not wait for a portal response before securing the account. Contact the bank through its official emergency channel, request card or account protections, and make a written record of the time and agent who helped you. Afterwards, use the appropriate complaint route to question unauthorised activity or poor handling.
A practical complaint timeline
Create a dated list with four columns: what happened, the evidence, who was contacted, and the response received. A timeline separates the original banking problem from delays caused by later complaint handling. If you receive inconsistent answers, quote the exact correspondence and ask the institution to reconcile the contradiction, rather than submitting numerous duplicate complaints.
What SBP Sunwai Complaint Portal actually means
The SBP Sunwai Complaint Portal is an official channel for banking customers to submit and monitor grievances. It connects the complaint to the appropriate institution or oversight forum; it does not approve loans, cancel a debt or guarantee that a disputed charge will be refunded.
Related reading: Find the SBP Housing Finance Documents 2026 guide on SchemesInfo.
A practical way to understand SBP Sunwai Complaint Portal is to ask which problem it solves, which organisation is responsible and what the applicant actually receives.
How to register and submit a Sunwai complaint
Use this sequence to organise the process. Where the subject is a regulatory rule or complaint service rather than a loan programme, the steps refer to the correct official process instead of pretending that there is a cash-benefit application.
- Start with the bank’s official Complaint Management Unit or dedicated complaint channel and retain the acknowledgement.
- Check whether the bank has replied within the applicable time and whether the answer addresses your issue.
- Open sunwai.sbp.org.pk from SBP’s website rather than from an advert or unsolicited message.
- Register or sign in using the genuine portal and supply requested identification/contact details.
- Choose the institution and complaint category that closely matches the problem; avoid unsupported accusations.
- State the dates, amounts, relevant transactions, prior complaint reference and precise remedy requested.
- Attach clear supporting copies without passwords, PINs or full card credentials.
- Submit, save the tracking/reference number and revisit the portal to monitor requests for information.
- Escalate to the Banking Mohtasib or another competent forum only as permitted for the complaint type.
Before taking any step concerning SBP Sunwai Complaint Portal, check the correct authority’s website for the current process and keep your acknowledgement or reference.
How the process works in everyday situations

Choosing the correct complaint forum
The bank’s own complaint unit is generally the first stop. A case about a bank’s failure to respond, disputed charges, account handling or collection conduct may later be considered by the Banking Mohtasib. Some matters, including selected microfinance and urgent-service concerns, may involve SBP. The portal helps users navigate these routes, but the correct recipient depends on the underlying issue.
- Record the original bank contact first; do not assume every banking complaint goes straight to SBP.
Writing a complaint that can be investigated
A useful complaint is a small evidence file, not an emotional message. Begin with the exact date of the event and the product involved. Next describe what the bank did, what you did in response and which documents support your account. End with a specific outcome you seek: correction of an entry, an explanation, a written decision or reconsideration of a charge.
- Separate confirmed facts from your interpretation; attach relevant pages rather than a full unredacted statement.
Related reading: Find the Loan Application in Pakistan guide on SchemesInfo.
People researching SBP Sunwai Complaint Portal should verify every stage directly and make a note of who is responsible for the next action.
Amounts, fees, security and practical costs
| Consideration | What to check |
|---|---|
| Portal access | Do not pay third-party “complaint activation” fees. |
| Repayment | Filing a complaint does not suspend a legitimate contractual obligation. |
| Refunds | Any refund or correction depends on verified facts and the forum’s decision. |
| Timeline | Use the timeframe applicable to the institution and category; 45-day rule commonly governs Mohtasib escalation. |
| Privacy | Never submit a banking password, PIN or OTP to a complaint agent. |
Before signing a declaration, accepting a disbursement or handing over property or guarantee papers, request current written terms from the official organisation. Administrative fees and repayment obligations can materially change the practical cost.
Any cost associated with SBP Sunwai Complaint Portal should be supported by an official fee schedule, bank disclosure or authorised receipt—not an agent’s verbal promise.
Build a stronger, clearer evidence file

Handling an unauthorised transaction
If you see a transaction you did not authorise, promptly contact the bank’s fraud and card-security channel to block further misuse; do not wait for a formal escalation. Keep the exact timestamp, merchant descriptor and channel from the statement. The complaint process then addresses investigation and potential correction.
- A complaint is not a replacement for urgent account-security action.
Tracking and follow-up
Save the case number and check the portal for requests for clarification. If the bank supplies a final answer, compare it with your own record and identify exactly which point remains unanswered. If you need to escalate, forward the earlier bank response and chronology instead of starting an unrelated narrative.
- Maintain one dated file with complaint references, attachments and received messages.
Organised records help people reviewing SBP Sunwai Complaint Portal understand a case without searching through unrelated images, messages or statements.
Three practical examples
The following examples illustrate sensible ways to read the published rules. They are not genuine recipient testimonials or promises of approval.
Unexplained fee
A current-account holder notices a new service charge. They ask the bank for the applicable schedule of charges and submit a dated statement excerpt. A Sunwai case becomes useful if the bank fails to explain or resolve the matter.
Delayed loan clearance
A borrower finishes payments but has not received a clearance letter. They retain receipts and their written request to the lender, then raise the missing document through the formal channel.
Card transaction dispute
A customer reports an unknown transaction and immediately secures the account with the issuing bank. The subsequent complaint includes the transaction reference, prior fraud report and investigation response.
The situations below illustrate how someone might evaluate SBP Sunwai Complaint Portal; they are educational examples rather than guaranteed approvals or remedies.
Common mistakes to avoid
Many delays begin with a preventable documentation or expectation mismatch. Check these points carefully before proceeding.
- Writing “bank is fraud” without naming the transaction and supporting facts.
- Submitting a complaint to a paid social-media agent instead of the official portal.
- Forgetting to retain the first complaint acknowledgement and reference number.
- Sharing complete card data, OTPs, PINs, passwords or remote-access permissions.
- Assuming a complaint automatically pauses repayment or guarantees a favourable outcome.
- Starting a new complaint each day instead of following the existing case trail.
A common mistake when considering SBP Sunwai Complaint Portal is assuming the same conditions apply to every applicant, branch or programme phase.
Security, privacy and responsible decisions
Use official addresses rather than links sent by strangers. Never disclose an OTP, password, PIN or remote-access code. When identity information is required, make sure the organisation and the reason for collecting it are authentic. Keep receipts, tracking IDs and copies of signed forms. If a scheme asks for a guarantor, cheques, a mortgage or other security, obtain a written explanation and understand the legal implications.
SchemesInfo is independent and does not arrange loans, receive applications, verify CNIC numbers, collect programme fees or determine awards. If the advertisement promises guaranteed money in exchange for an advance payment to an individual account, treat it as a warning sign.
For SBP Sunwai Complaint Portal, never share an OTP, PIN, banking password or original document with anyone whose authority you have not independently checked.
Further programme detail that deserves attention

When this platform is not the right solution
Sunwai cannot award a new loan, remove an adverse credit history simply on request, or settle a personal transaction with no banking-service connection. Matters pending before a court or other excluded disputes may follow separate rules. For a question about loan eligibility or scheme terms, use the lender’s product information rather than the complaint form.
- Do not submit a loan application or financial-assistance request through Sunwai.
Related reading: Find the PM Youth Business and Agriculture Loan Scheme guide on SchemesInfo.
Details affecting SBP Sunwai Complaint Portal may change after a new official notification, so record the date of the source you rely on.
A complaint evidence matrix: match the issue to the proof
Different banking problems require different facts. For an ATM cash-not-dispensed case, the most useful record is usually the attempted transaction time, location, amount, account debit and any ATM receipt. For a loan statement dispute, focus instead on the instalment schedule, payment dates, contract clauses and any written rate-change notice. A debit-card transaction dispute calls for merchant and authorization details; an account-freeze complaint needs the notice and the customer’s earlier request for explanation. There is no advantage in uploading dozens of unrelated documents if the relevant entry is missing.
- For card or ATM issues: transaction date, amount, masked account/card identifier and bank reference.
- For loan-servicing issues: sanction letter, schedule, paid receipts and charge entry.
- For an account-opening or closure delay: completed request, bank acknowledgement and subsequent emails.
- For staff conduct: branch, official role, date, factual description and any witnesses or correspondence.
Related reading: Find the Asaan Karobar Finance guide on SchemesInfo.
These practical checks make SBP Sunwai Complaint Portal easier to use without confusing a published rule with a personal eligibility decision.
What a useful final bank response should address
When a financial institution replies, compare its response against the exact questions you asked. Did it identify the disputed entry and explain the basis of its position? Did it supply a calculation, reference a relevant product term, or merely repeat a generic statement? If the answer resolves one part but not another, write a short follow-up listing the unresolved points rather than starting an entirely new chronology. Remember that a disagreement by itself is not proof of misconduct: the documents and applicable rules matter.
- Match each disputed amount to a dated statement item.
- Check whether the answer is from the appropriate bank complaint unit.
- Save the final reply, its date and any promised resolution time.
- Escalate only those points that remain unanswered, with the earlier complaint reference.
When interpreting SBP Sunwai Complaint Portal, separate the official document requirement from optional evidence that makes an application easier to assess.
Protecting yourself after the complaint is closed
A closed complaint can still require practical follow-through. If a charge is reversed, verify it appears on the next statement; if a loan clearance letter is promised, obtain the actual signed letter; and if account details were compromised, continue to monitor the card and online-banking settings. Keep the case documents for a reasonable period consistent with your own record-keeping needs. A successful case should produce a traceable record of the remedy, not simply an oral assurance that someone will call back.
- Confirm any agreed correction against a subsequent account statement.
- Keep copies of the reference number, decision and final correspondence.
- Monitor unusual activity after a transaction-security incident.
- Ask for written confirmation where a document or account status was changed.
After taking action about SBP Sunwai Complaint Portal, save the result and check whether another step is actually required.
Which complaint forum should receive your issue first?
The SBP Sunwai Complaint Portal is not a replacement for a bank’s own complaint unit. The useful first decision is identifying whether the disputed service is provided by a commercial bank, Islamic bank, microfinance bank or another institution. That distinction can change the appropriate escalation route.
- For an unauthorised ATM withdrawal, contact the bank immediately to block access, then submit a written complaint and preserve the transaction reference.
- For a debit-card merchant dispute, collect the merchant receipt, transaction date, amount and any evidence that the merchant cancelled or refunded the sale.
- For a loan clearance or collateral-release complaint, retain the original settlement receipt and a copy of the bank’s promised document or deadline.
- For a complaint against a microfinance bank, confirm whether SBP rather than Banking Mohtasib is the relevant subsequent forum.
- For a court-pending dispute, ask for qualified legal advice on jurisdiction; the complaint portal cannot override a court proceeding.
SBP’s public guidance explains that the bank’s complaint management unit is generally the first forum. A dissatisfied customer of an eligible bank may approach Banking Mohtasib after the prescribed conditions, including the general 45-day response threshold. Do not interpret that period as a guarantee that every investigation will finish within 45 days.
How to draft a complaint the bank can actually investigate
The SBP Sunwai Complaint Portal works best when the underlying complaint is precise. Write a short factual account before opening the form; this helps avoid leaving out details while navigating a mobile screen. Keep a separate copy of your narrative.
- Identify the account or product by a masked reference rather than publishing the complete number.
- State the date and approximate time of the event; if several transactions are involved, list each separately.
- Give the amount disputed and explain what you expected to happen instead.
- Describe whom you contacted at the bank, when you contacted them and what acknowledgement or answer was provided.
- Request a specific outcome, such as a written explanation, correction of an erroneous charge or release of a promised letter.
- Attach only documents that support the allegation; label screenshots with dates and avoid sharing passwords or one-time codes.
For example, a useful explanation is: “On 12 October I reported an ATM debit of Rs 12,000, reference XXXX. The cash was not dispensed. I received complaint number YYYY but no written decision. Please investigate the transaction, explain the finding and correct the account if warranted.” This is a template, not a prediction of the bank’s conclusion.
Create a safe follow-up timeline
Once a complaint is filed through the SBP Sunwai Complaint Portal, keeping a timeline prevents missed replies and duplicate cases. Create a simple table or note on your phone. The goal is to track evidence, not to send repeated complaints every day.
- Day filed: record the date, complaint number, selected bank or forum, and the acknowledgment screenshot.
- When the bank requests clarification: respond with the exact requested evidence and save the request as well as the response.
- After a phone call: note the staff member’s designation, agreed next action and any expected communication date.
- On receiving an interim answer: check whether it names the disputed transaction and gives a realistic next step.
- On a final reply: compare every conclusion with your original complaint and supporting documents.
- If escalation is needed: attach the earlier complaint number and correspondence rather than starting with an unrelated narrative.
A complaint status marked “closed” is not proof that the requested remedy happened. If the bank agrees to reverse a charge or issue a clearance certificate, verify the actual account entry or document. Retain the final response so a later reviewer can follow the sequence.
Recognising technical problems versus substantive disputes
Occasionally the SBP Sunwai Complaint Portal may be unavailable, an upload may fail or a notification may not arrive. Treat those as technical access problems, which are different from a dispute about the bank’s decision. Solving an access issue does not automatically resolve the underlying complaint.
- Try the official URL from SBP’s website and avoid look-alike pages reached through advertisements.
- Check whether a file is within the portal’s permitted format or size before attempting another upload.
- Use a stable connection and save a local draft of the complaint narrative before resubmitting.
- Do not open several parallel complaints solely because a confirmation message is delayed; first check the account dashboard.
- For inaccessible accounts, use the portal’s published help routes rather than sending sensitive documents to strangers on social media.
If there is immediate card fraud, call the bank’s official fraud helpline independently of portal availability. Blocking compromised access is a time-sensitive security step. The complaint record can then document the subsequent bank action and any remaining dispute.
What an effective resolution looks like
The purpose of the SBP Sunwai Complaint Portal is an accountable complaint process, not necessarily a refund in every case. Evaluate the quality of the response by comparing it to the question you asked. A professional reply should address the facts, cite a relevant term where necessary and explain any further remedy.
- Does the response identify the disputed transaction, branch, product or document?
- Does it explain how the bank reached its conclusion and what information it reviewed?
- If a correction was promised, is there an observable reversal, letter or amended account record?
- If the bank declines the request, does it explain the applicable reason rather than merely using a generic template?
- Does it identify an appropriate next complaint forum when further review is legally available?
Where the explanation is incomplete, write a targeted follow-up that identifies the exact unanswered point. Avoid threatening language and keep copies of communications. Your strongest record is a clear timeline, relevant documents and a precise request that can be checked against the bank’s final action.
Final five-minute checklist before proceeding
- I identified the actual authority and located its official web address.
- I confirmed the live programme or service status and read the newest notice.
- I reviewed the published eligibility and prepared only relevant documents.
- I understand any fees, security, repayment terms and conditions.
- I can explain my reason for applying or complaining in a clear, factual way.
- I saved the official reference number and copies of submissions and correspondence.
Use this checklist before relying on SBP Sunwai Complaint Portal, then follow the issuing organisation’s instructions if anything differs.
Frequently asked questions
Is SBP Sunwai Complaint Portal for new loans?
No. It is for banking complaints. Loan and financing applications belong to banks or approved programme portals. The SBP Sunwai Complaint Portal can help with a loan-servicing dispute, but it does not issue new financing or approve applications.
Do I need to contact my bank first?
Generally yes. The bank or MFB complaint management unit is the primary forum; retain its reference number and decision. A record of your first bank complaint helps the SBP Sunwai Complaint Portal direct an unresolved grievance to the proper forum.
Can I file anonymously?
The official guidance expects identifiable complainant and contact information. Anonymous complaints may not be investigated. Registration for the SBP Sunwai Complaint Portal requires identification and contact details so the complaint can be followed up.
How long should I wait before approaching Banking Mohtasib?
The general threshold is 45 days without a satisfactory response, subject to the specific law and complaint type. The SBP Sunwai Complaint Portal does not replace the legal requirements that apply when escalating eligible bank complaints.
Can the portal guarantee a refund?
No. Remedies depend on investigation, evidence, applicable rules and the competent forum. A refund requested through the SBP Sunwai Complaint Portal depends on the evidence, investigation and lawful decision of the appropriate forum.
Can I complain about a microfinance bank?
Yes, within the applicable framework. The correct forum and escalation route can differ from ordinary commercial-bank matters. The SBP Sunwai Complaint Portal accepts complaints within the applicable banking framework, but microfinance-bank escalation rules can differ.
Is there a registration charge?
No official scheme should require a private agent fee merely to activate a complaint. For SBP Sunwai Complaint Portal, check the appropriate official authority if circumstances differ from the general explanation above.
What if my account may be compromised?
Contact the bank fraud/card-security team immediately, secure the account and then document the complaint.
What should I upload?
Relevant statements, screenshots, correspondence and references, with unnecessary private information removed.
Where can I check complaint status?
Use the status or tracking feature in the official Sunwai portal and your stored complaint reference.
Primary sources and date checks
This independent guide is informational, not a government application service. Confirm the current application window and individual terms directly with the issuing authority before providing identity documents or making commitments.