ZTBL Tractor Loan: Is Buying Better Than Hiring?
Compare Ownership, Insurance And Hire Costs.
The Short Answer
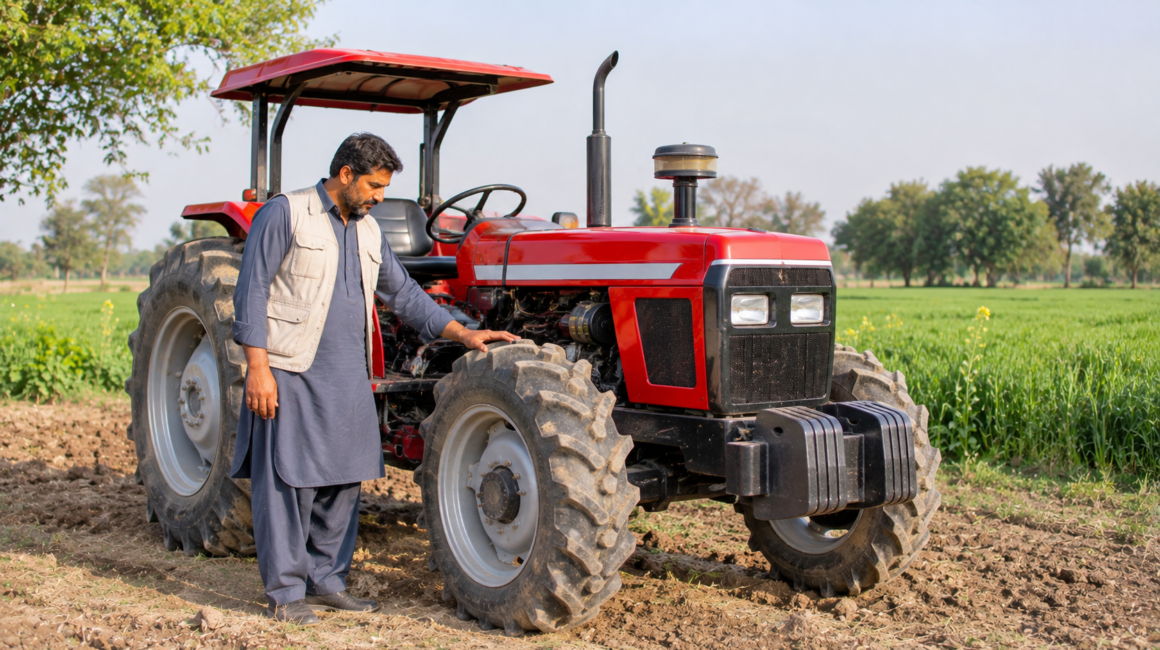
ZTBL’s conventional tractor loan is offered through its branches for farmers with suitable owned and possessed agricultural land. The published ceiling is PKR 2.5 million, borrower contribution is 10% of the loan amount and the repayment period is eight years, in half-yearly instalments starting six months after first disbursement. The page describes manufacturer/dealer payment, joint registration and comprehensive insurance. A quoted insurance percentage or fee should be confirmed from the latest branch schedule rather than treated as a permanent rate.
Table Of Contents · 10 Useful Sections
- What ZTBL Actually Publishes
- Documents And Evidence To Prepare
- Calculate Whether Owning Beats Hiring
- Tractor Ownership: A Useful Cost-Per-Hour Comparison
- Repayment, Timing And Affordability
- Avoidable Errors And Fraud Checks
- Deeper Decision Checks Before You Borrow
- ZTBL Tractor Loan: A Practical Reader Workbook
- Compare The Cost Before You Sign
- Frequently Asked Questions
What ZTBL Actually Publishes
ZTBL’s conventional tractor loan is offered through its branches for farmers with suitable owned and possessed agricultural land. The published ceiling is PKR 2.5 million, borrower contribution is 10% of the loan amount and the repayment period is eight years, in half-yearly instalments starting six months after first disbursement. The page describes manufacturer/dealer payment, joint registration and comprehensive insurance. A quoted insurance percentage or fee should be confirmed from the latest branch schedule rather than treated as a permanent rate.
You can check the original product sheet directly: ZTBL Official Financing Page
Eligibility: Who Can Realistically Qualify
For ZTBL Tractor Loan, ask the branch which written eligibility rule is decisive for your proposed activity rather than relying on a general advertisement.
ZTBL Tractor Loan Scheme enables qualifying land-owning farmers to finance a new tractor through the bank rather than receiving a government subsidy.
- Be a farmer with appropriate self-owned and self-possessed agricultural land to justify tractor finance.
- Apply through ZTBL; the product is listed at all branches.
- Plan to purchase a qualifying new tractor or a permitted farm-transport vehicle for agricultural purposes.
- Be able to supply acceptable security and the published 10% borrower contribution.
- Pass the bank’s credit review and show repayment capacity over the stated instalment period.
- Understand that this is bank financing with prevailing markup, not automatic eligibility for Punjab’s separate tractor subsidy.
ZTBL currently describes a maximum of Rs. 2.5 million per party, an eight-year recovery period with half-yearly instalments, and a six-month commencement period after first disbursement. Applicants should get a written quote for all bank and insurance costs.
Documents And Evidence To Prepare
ZTBL Tractor Loan Scheme requires land and identity documents and uses a dealer-payment process, with additional registration and insurance steps after sanction.
- CNIC copy and completed ZTBL application form.
- Agricultural passbook/Fard Jamabandi showing the relevant land holding.
- Two recent applicant photographs, as specified by the bank.
- Manufacturer or dealer quotation to support the proposed tractor payment; the bank pays the seller after approval.
- Security documentation in the form acceptable to ZTBL.
- Joint tractor registration and comprehensive insurance paperwork during disbursement, as required by the bank’s published terms.
Match the proposed tractor’s horsepower and equipment to actual farm size. A repayment schedule should still be affordable in a poor harvest year; compare purchase finance with hiring machinery if annual utilisation will be low.
Official Terms Of ZTBL Tractor Loan
In a ZTBL Tractor Loan application, the cost of inputs or equipment must be supported by current supplier quotations rather than an untested guess.
These are the published rules on the named authority’s website. A maximum finance amount is not an offer or a promise of approval. Always request updated product details before submitting original documents or accepting financing.
| Key question | Published position and what it means |
|---|---|
| Applicant | Farmer with enough self-owned and self-possessed agricultural land to support the tractor’s feasibility. |
| Vehicle | New tractor or eligible farm transport vehicle under approved purpose and quotation. |
| Published maximum | Up to PKR 2.5 million per borrower or party. |
| Own equity | 10% of the loan amount is deposited and adjusted against tractor price. |
| Disbursement | ZTBL pays the manufacturer/dealer through a pay order or demand draft against the accepted quotation. |
| Registration | The tractor is jointly registered in the bank and borrower names and comprehensively insured. |
| Term | Up to eight years, half-yearly instalments beginning six months after first disbursement. |
Calculate Whether Owning Beats Hiring
The most useful way to approach ZTBL Tractor Loan is to turn the headline into a written, testable plan. These are decisions the actual borrower can check, rather than promotional claims or guaranteed outcomes.
- List your annual tillage, sowing, hauling and irrigation-related tractor hours before choosing horsepower.
- Ask local contractors what hiring comparable machinery would cost during peak season and how much waiting time causes lost crop value.
- If planning custom hire for neighbours, gather realistic local rates and expected bookings rather than assuming the tractor works every day.
- Calculate diesel, lubricants, tyre wear, periodic servicing, driver costs, shed space and unexpected breakdown reserves.
- Divide the full annual ownership cost by productive hours; compare that figure with actual hire quotations.
Why It Matters Now
A well-prepared proposal is specific: it shows not only the purchase or working-capital need but also the timing of expected benefits and the evidence supporting each amount. For ZTBL Tractor Loan, this means making the next step on written facts rather than expecting an institution or seller to resolve every uncertainty after approval.
Read The Financing And Insurance Contract Closely
A ZTBL Tractor Loan applicant should record actual income dates beside the scheduled bank instalments, not only project the annual total.
Official eligibility is only the beginning. Before taking on this commitment, measure the costs and constraints that arise in the real business or household setting. The points below are practical checks, not a substitute for a bank appraisal.
- ZTBL’s published loan ceiling may be smaller than the quoted new tractor price; work out cash needed above the approved amount.
- The published 10% equity contribution does not remove registration, insurance, accessories and dealer delivery costs.
- Get written confirmation of the bank’s joint registration and whether transfer restrictions apply while the loan is outstanding.
- Compare the complete insurance premium and claims process, not just a one-line percentage in an old article.
- Check whether a model or dealer quotation is accepted and when the payment order is released.
Evidence To Collect
Keep dated quotations, identity and security records, realistic operating notes and a short income forecast. If a fact cannot be independently verified, label it as an estimate. For ZTBL Tractor Loan, this means making the next step on written facts rather than expecting an institution or seller to resolve every uncertainty after approval.
Tractor Ownership: A Useful Cost-Per-Hour Comparison
A tractor is valuable when it is used enough. Fuel, tyres, servicing, insurance, driver and debt expense continue to matter even if the tractor is idle for part of the year.
Illustrative Calculation — Not A Bank Quotation
Four Checks Before Signing
- Use field size and required work to estimate annual hours realistically.
- Ask the dealer for full on-road and attachment costs.
- Include registration and comprehensive insurance in the plan.
- Keep a maintenance reserve for the busiest crop season.
Replace the example figures with your own verified costs and the lender’s signed term sheet. An attractive headline ceiling tells you nothing about your eventual approval or overall cost.
Costs, Pricing And Borrower Contribution
Before accepting ZTBL Tractor Loan, check how a lower-selling-price scenario changes cash remaining after food, transport, wages and maintenance.
Any serious guide to ZTBL Tractor Loan Scheme must separate headline financing limits from the amount actually received, and also separate fees from interest or markup. The relevant cost factors are owner contribution, tractor price beyond the approved limit, insurance premium, registration, diesel, servicing, tractor shed and seasonal implement repairs.
Ask for a written cost schedule that distinguishes principal, borrower contribution, appraisal or processing charges, insurance, taxes, documentation, collateral registration and any penalties. A product advertised as interest-free can still involve repayments; a conventional bank product can have a variable markup rate that cannot be predicted from a static article.
The value of an investment is not measured by the cash released at the start. The question is whether the project produces enough benefit to justify ongoing obligations. Under ZTBL Tractor Loan Scheme, the applicant should compare reliable income or savings with operating expenses over a full year, including less favourable months.
Build a contingency margin into the ZTBL Tractor Loan rather than counting every rupee of potential income as spendable. If an item becomes more expensive between quotation and disbursement, clarify who covers the difference. Never make an unofficial payment to a person claiming to guarantee finance approval.
Repayment, Timing And Affordability
The published repayment or financial obligation for ZTBL Tractor Loan Scheme should be understood carefully: half-yearly instalments over eight years, beginning after a six-month first-disbursement period; development markup rate depends on bank rules and is not assumed to be zero.
Where instalments are half-yearly, calculate the six-month cash requirement from monthly income rather than waiting for the due date to discover a shortfall. If income is seasonal, reserve part of each profitable sale toward the next payment. Keep borrowing for a productive activity distinct from routine family spending.
Interest or markup, when applicable, can change the true cost substantially. Request an illustration showing total payable under current terms and what happens if a payment is late. For ZTBL Tractor Loan Scheme, never calculate a repayment using a rate or duration found on an unofficial social-media card.
The safest affordability test asks what happens when sales, harvest output, wages or expected benefits are below plan. A project that works only under the best scenario leaves the borrower exposed. Consider smaller financing, waiting for more savings or choosing an alternative scheme if the minimum realistic outcome cannot support payments.
The ZTBL Tractor Loan Scheme includes joint vehicle registration and comprehensive insurance.
ZTBL Tractor Loan Scheme farmers should assess annual machine use, maintenance and fuel alongside each instalment.
Working Examples And Decision Tests
The documentation for ZTBL Tractor Loan should explain any variation between the land record, borrower identity and the business location.
A tractor should be chosen for the farm's work, not for the marketing photograph. List the acreage, soil conditions, tillage passes, irrigation needs and implements that will be attached. Higher horsepower can increase fuel and maintenance costs without adding value on a small holding. A dealer's quote should identify the exact model, specifications, warranty and after-sales workshop availability.
ZTBL's published tractor product calls for a 10 percent borrower contribution and disburses the approved amount by pay order or draft in favour of the manufacturer or dealer. This is different from receiving unrestricted cash. The bank also requires joint registration and comprehensive insurance, so the borrower should understand who holds the documents and what happens when the finance is fully repaid.
Eight years is a long operating period for a machine that works in dusty fields. Budget annual oil and filter changes, tyres, repairs and a safe storage area. In a weak harvest year, tractor hire income from neighbouring farms may help only if demand actually exists; it should not be used as the sole basis for a large scheduled instalment.
Do not confuse ZTBL's tractor loan with a Green Tractor subsidy allocation. A subsidy reduces the purchase price for eligible selected applicants, while a conventional bank loan remains repayable with its contractual markup. Someone comparing them should write two separate cash schedules and confirm current availability before entering an obligation with a dealership.
ZTBL Tractor Loan Scheme financing is repaid through instalments rather than awarded as a subsidy.
A larger tractor may be useful for a big holding but costly for a small one. Compare expected hours of operation, fuel and repairs, seasonal rental alternatives and the revenue from permitted transport activity before choosing a model.
Avoidable Errors And Fraud Checks
Common mistakes around ZTBL Tractor Loan Scheme include assuming a tractor subsidy and a bank loan are the same thing, purchasing before sanction, ignoring insured registration and choosing an oversized model. Each is avoidable with documented verification and a realistic financial plan.
One warning sign is anyone asking for a processing payment to a personal wallet while promising certain approval. Legitimate public agencies, lenders and registered partners can provide identifiable locations and formal receipts. If something looks suspicious, end the conversation and contact the institution through its own published channel.
Another mistake is basing major purchases on a policy that may no longer be accepting applications. Keep any historical phase information separate from current operational status. Do not interpret an old launch announcement or the mere presence of a web form as confirmation of available funding.
A third problem is publishing sensitive personal details online to ask for informal “eligibility checking.” Bank staff should use authorised secure processes. Readers exploring ZTBL Tractor Loan Scheme should not publish CNIC scans, property documents, bank credentials or one-time verification codes in public groups.
Plan For Seasonality And Machine Downtime
An important question about ZTBL Tractor Loan is which collateral or family guarantee would remain at risk if projected sales did not happen.
This section addresses the costly mistakes that a short online application guide often misses. Keep records of the assumptions, ask the bank for the current product conditions and adjust the proposal to the reality of the intended activity.
- Half-yearly instalments need funds even if rain delays fieldwork or harvest returns fall short.
- Keep spare filters, common service items and maintenance contacts locally so a small fault does not strand the tractor.
- Budget safe storage and driver training; misuse or poor maintenance may affect insurance and resale value.
- Separate money for equipment attachments that are not included in the tractor sale quote.
- Keep an operating log with hours, trips, fuel and repair invoices to evaluate whether the tractor is paying its way.
The Decision Threshold
Pause when the figures work only under optimistic conditions. Better information, a smaller pilot or an alternative to borrowing may protect the family or business from an avoidable obligation. For ZTBL Tractor Loan, this means making the next step on written facts rather than expecting an institution or seller to resolve every uncertainty after approval.
Deeper Decision Checks Before You Borrow
These product-specific checks help readers go beyond headline figures. Work through the details in the context of your own farm, household or business and compare the answers with current official requirements.
Comparing Machine Utilisation And Hiring
- Estimate annual hours of ploughing, tilling and hauling on land actually available to the borrower; record which tasks need particular attachments.
- Quote local tractor hire rates for peak-season work and calculate the saving from owning after accounting for diesel and the operator.
- If the business plan includes custom hire, verify genuine local demand and the time available outside the borrower’s own fieldwork.
- Budget a low-use year where rains or fuel costs reduce tractor hours; check that instalments remain payable.
Understanding The True Purchase Price
- Get a current official dealer quote with model, horsepower, taxes, delivery charges, attachments and warranty line items.
- Compare the whole cash requirement with ZTBL’s published financing ceiling; the bank may not fund the entire tractor price.
- Review joint registration, lien release, insurance renewals and any restriction on selling the tractor before the loan is cleared.
- Ask whether the current insurance price differs from historical figures and understand excesses and excluded events.
Making The Tractor Earn Its Keep
- Keep a log of hours, fuel and work undertaken for each crop or outside customer, then reconcile it with income received.
- Schedule servicing before the busiest fieldwork weeks, and keep funds for tyres, filters, belts and unexpected repairs.
- If a driver is hired, budget legal employment costs, training and safe use rather than relying on unpaid labour.
- Compare the actual first-year ownership cost to the original projection before making further machinery purchases.
Write down the assumptions that still need verification and take that list to the authorised bank or office. If the plan only works when sales, harvests or repayment conditions are perfect, reduce the proposed commitment before signing.
Three Real-World Decisions To Think Through
For ZTBL Tractor Loan, a bank-approved limit is a borrowing cap rather than a recommendation to use the entire amount.
The situations below are illustrative, not actual applicants or guaranteed results. Compare the detail that changes the correct decision: location, income timing, project operations or eligibility.
A Smallholder With Occasional Tillage
A farmer uses a tractor for only several days each season. Hiring may be financially better once insurance, fuel, repair costs and half-yearly instalments are included.
A Larger Farm Offering Custom Work
An operator cultivates enough land to use the tractor regularly and has genuine demand from neighbouring farms. A business plan identifies off-season downtime and forecasts paid hours conservatively.
A Buyer Surprised By Price Differences
The dealer’s quotation exceeds the bank’s financing limit. Before paying a deposit, the buyer asks the bank what contribution, registration and equipment extras must come from personal savings.
Use the scenarios as prompts for your own figures. If your location, project design or income differs, the likely bank assessment can also differ. Save written quotes, identify which assumptions are uncertain and revisit them before committing.
Final Checklist Before Committing
A strong final preparation list for ZTBL Tractor Loan Scheme is: prepare land proof, realistic annual acreage, dealer quote, total cost schedule, insurance and replacement-parts budget and instalment cash flow.
Write down the source of each important figure, particularly the maximum loan, eligibility rule, repayment term and named application channel. Record the date you checked it. Scheme rules can change while an older article remains visible in search results; a careful reader treats the latest official notice as authoritative.
Before submitting anything, ask one final question: would this still be a good decision if approval were delayed, the amount were smaller, or the economic benefit arrived later? If not, revise the budget or postpone commitments. The purpose of ZTBL Tractor Loan Scheme should be genuine resilience and productive benefit, not an unnecessary financial burden.
Keep complete copies of the final application, lender or agency messages, signed terms, payment receipts, supplier invoices and any subsequent updates. This protects the applicant during disputes and makes the long-term outcome easier to measure, whether the ZTBL Tractor Loan is a household improvement, an agricultural business or an education expense.
ZTBL Tractor Loan Scheme tractor payments follow bank-approved dealer and registration arrangements.
ZTBL Tractor Loan: A Practical Reader Workbook
Borrowers considering ZTBL Tractor Loan should ask what documentation is required after disbursement to prove that the money funded the intended project.
Use these additional checks to turn the official rules into a project you can explain and defend. They are tailored to this type of financing and should be completed with actual quotations and local information.
Tractor Suitability And Total Ownership
- Compare machine horsepower with actual implement width, field size, soil and terrain. A powerful tractor can be uneconomical on fragmented small plots.
- Get written dealer quotations for tractor, registration, delivery, attachments and first maintenance service before estimating the required financing.
- Include fuel, tyres, lubricants, operator wages, downtime and servicing in per-acre costs, not just the instalment amount.
- If custom-hiring income is part of the repayment plan, obtain credible nearby customer demand and account for peak-season competition.
- Compare total ownership cost with renting equipment for each crop season; renting can be the better decision for small annual operating hours.
Collateral, Insurance And Repayment
- ZTBL publishes joint bank-and-borrower tractor registration and comprehensive insurance; ask for the insured risks and exclusions.
- Clarify that the published tractor insurance premium is quoted at 1.99% on the product page and confirm the current charged amount in the branch illustration.
- The published product provides up to eight years with half-yearly instalments starting six months after first disbursement, subject to the actual contract.
- Ask whether a dealer invoice, factory delivery period or any subsidy-related process may alter the disbursement timetable.
- Do not purchase a tractor merely because a financing ceiling is available; check the additional cash you must supply and the effect of a weak harvest.
How To Apply For ZTBL Tractor Loan: Six Careful Steps
For readers searching for an online application, it is important to distinguish enquiry, portal registration, bank appraisal and final sanction. These are not interchangeable milestones.
- Start with the official product: Open the issuing authority’s named product page, check the current operating status, and verify the correct branch or portal for your district.
- Confirm that you qualify: Use the published facts table to check purpose, geography, creditworthiness, contribution and any age or experience requirement. Do not change the truth to fit the product.
- Build the project plan: List each funded item, operating cost, expected income timing and the evidence behind the numbers. Obtain genuine supplier or buyer quotes.
- Get the full finance illustration: Ask the institution for the current markup, fees, security rules, repayment dates, late-payment consequences and total amount payable.
- Submit only through verified channels: Share CNIC, land records and private finances only through the official bank or authorised government system. Preserve the reference number.
- Review the sanctioned terms: Read all conditions before signing or paying a supplier. Approval amounts, security, insurance and disbursement stages may differ from the application.
Official ZTBL Sources And Help
These links lead to the relevant bank or government sources. Scheme Info is an independent information website, not a lender or government application office. Rules can change and decisions rest with the named institution.
Practical Decisions That Protect Your Budget
Compare A Tractor With Local Hiring First
Write down the number of acres to cultivate, the actual operations needed and the days the machine would be productive. Include other farmers who might pay for custom work only if agreements or realistic demand exist. A tractor used for a few busy weeks can have a high cost per productive hour after fuel, drivers, tyres, repairs, registration and financing. Compare that annual ownership cost with genuine local hiring quotations.
Match Tractor Size To Fields And Implements
More horsepower is not always better for a small or fragmented holding. Check soil conditions, field access, irrigation channels, intended attachments, service access and fuel consumption. A locally repairable tractor with readily available parts may be financially safer than a larger model with long downtime. Ask for at least two formal dealer quotations and match the model to the approved finance amount.
Understand Joint Registration And Insurance
ZTBL’s public terms describe joint bank-borrower registration and comprehensive insurance. This is not the same as owning an unrestricted vehicle from the first day. Ask when the bank’s interest is removed, who pays insurance renewals, whether damage claims affect repayments and what happens after sale or loss. Confirm any published insurance premium against the current quotation rather than assuming it cannot change.
Model Repayments During The Low Season
Annual crop earnings may arrive only once or twice, while repairs and household bills arrive throughout the year. Reserve funds before the harvest is sold and ask whether half-yearly instalments fall after the cash-generating season. ZTBL Tractor Loan has an eight-year published period with instalments beginning six months after first disbursement, so a tractor that becomes productive late can still generate an early cash shortage.
Check The Full Tractor Acquisition Cost
A PKR 2.5 million loan ceiling does not mean every suitable new tractor can be financed without substantial additional money. Add purchase price, the bank’s required equity, insurance, registration, delivery, attachments and working fuel. Confirm that the dealer-payment method and quotation are acceptable to the lender. Do not hand an informal deposit to a supposed loan intermediary who promises immediate sanction.
Your ZTBL Branch-Visit Checklist
Before approaching the branch about ZTBL Tractor Loan, make a file that links your identity, activity, budget and ability to repay. ZTBL can assess collateral, past borrowing and project viability even when the public product appears to fit your circumstances. Do not assume the published maximum is an individual sanction or a guaranteed subsidised interest rate.
- Carry your valid CNIC, recent photographs and the latest agricultural land record where applicable.
- Bring written quotations or realistic invoices for the specific equipment, stock, animals or inputs to be financed.
- Prepare expected income and all operating costs for a good, normal and difficult season.
- Ask for the prevailing markup rate, documentation charges, collateral and insurance terms in writing.
- Confirm whether a family or group co-applicant is legally responsible for repayment.
- Request a dated repayment schedule and a receipt or application reference for follow-up.
Compare The Cost Before You Sign
The table below is a decision worksheet, not a statement that an application will be accepted. Write the numbers quoted by the branch next to your own figures. Where a cost changes with time, ask for the method used to calculate it.
| Budget Question | Evidence To Collect |
|---|---|
| Is the amount enough? | Product ceiling, borrower cash contribution and supplier quotations. |
| Can I pay on time? | Dates of receipts, crop harvests or customer payments versus instalment dates. |
| What if sales fall? | Conservative loss scenario and emergency cash reserve. |
| What is the total cost? | Written markup, loan fees, insurance, transport, storage or asset upkeep. |
| What is at risk? | Land or family guarantees, pledged goods, equipment and default consequences. |
| What proves the decision? | Official ZTBL product page, branch written terms and application acknowledgement. |
What To Do Next
If ZTBL Tractor Loan could match your needs, open the ZTBL product page, identify the branch that handles your area and request a current written product sheet. Prepare a realistic project file, compare at least one alternative way to finance the activity and avoid agents promising guaranteed approvals or demanding private transfers. A branch enquiry is not an obligation to take the loan.
For general product information and branches, use the bank’s official site: ZTBL Agriculture Loans
Frequently Asked Questions
These answers focus on decisions readers need to make. Where current bank terms are not published, ask the authority for a written response rather than using an invented fixed rate or deadline.